
Blogs
Path of Exile 2 rewards players who treat equipment as a long-term plan rather than a series of quick replacements. Whether a character is entering early maps or preparing for difficult encounters, POE 2 Items can help fill crucial gaps in damage, defenses, and utility while a build takes shape.
The most successful players usually focus on a small number of meaningful upgrades. A well-chosen weapon, a reliable defensive layer, and properly matched accessories often provide more value than repeatedly changing every slot after each new drop.
Build Around a Clear Item Priority
Every build has one or two stats that determine whether it feels smooth in actual combat. A melee character may depend on weapon damage and attack speed, while a caster may value spell levels, mana support, or cast speed. Before comparing item options, identify the statistic that most directly improves the character's main skill.
Defensive needs should come immediately after offensive priorities. Elemental resistance, life, energy shield, evasion, armour, and recovery all matter, but their relative importance changes with the passive tree and skill setup. An item that looks modest on paper can become excellent when it completes a missing layer of protection.
Know Which Slots Create the Biggest Difference
Not all equipment slots carry equal weight. Weapons and certain skill-focused pieces can transform clear speed or boss damage, while rings, belts, and boots often solve resistance, movement, and resource problems. Spending attention where the impact is greatest keeps progression efficient.
The following comparison offers a practical way to judge upgrade potential during a new stage of progression.
| Item Slot | Common High-Value Focus | When to Upgrade |
|---|---|---|
| Weapon | Base damage, skill scaling, speed | When encounters become slow |
| Body Armour | Defenses, life, sockets, key modifiers | When survival becomes inconsistent |
| Rings and Belt | Resistance, attributes, recovery | When build requirements are unmet |
| Boots | Movement speed and defensive stats | When positioning feels difficult |
It is also worth keeping a backup set of accessories. Swapping a ring or belt for a specific encounter can be easier than rebuilding the entire character, especially when one resistance or attribute requirement is temporarily more demanding.
Evaluate Value Beyond the Tooltip
A strong item does more than raise a visible number. It can free passive points, allow a support gem change, reduce flask pressure, or make difficult movement patterns safer. These indirect benefits are often what separate a functional setup from one that feels dependable across long sessions.
Players should also consider flexibility. Gear with broadly useful modifiers remains valuable when testing different skills or adjusting a build after finding a new unique item. Highly specialized pieces can be powerful, but they may limit future choices if the rest of the setup changes.
Make Each Upgrade Serve the Next Goal
Progression feels best when every purchase or drop has a purpose: reaching a resistance target, improving a main damage source, surviving a difficult boss, or preparing for higher-tier content. This approach prevents wasted currency and keeps the character moving forward with confidence.
For players who want to complete those upgrades without losing momentum, choosing to buy Path of Exile 2 Items can be a practical way to refine a build and stay focused on the next challenge.
Worldwide Autonomous Drilling Robots: How 16.25% CAGR Reshapes Mining and Energy Markets
By pmarketresearch, 2026-09-18
Navigating the Autonomous Drilling Robots Market: Strategic Trends and Commercial Opportunities Through 2032
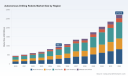
Market Momentum and Defining Challenges The worldwide autonomous drilling robots market has entered a phase of accelerated expansion, with revenue scaling from approximately 450.4 million USD in 2020 to an estimated 945.5 million USD by 2025. Projections indicate the market will surpass 1.1 billion USD in 2026 and continue its upward trajectory, reaching roughly 2.7 billion USD by 2032. At a compound annual growth rate of 16.25 percent across the forecast period, the sector reflects a structural shift rather than a cyclical uptick. This growth is underpinned by the maturation of sensing technologies, tighter safety mandates, and the escalating complexity of extraction and construction operations in remote or hazardous environments. Despite the compelling demand signals, the industry is navigating several critical junctures. First, the transition from semi-autonomous to fully autonomous systems demands a convergence of hardware reliability, real-time geotechnical feedback, and fleet-level orchestration that remains unevenly distributed across regions and applications. Operators are weighing the operational benefits of removing personnel from high-risk drilling zones against the capital intensity of sensor fusion suites, positioning systems, and adaptive control algorithms. Second, standardization and interoperability are emerging as practical bottlenecks. As drilling fleets grow more automated, the ability to integrate disparate rig platforms, data pipelines, and remote command centers becomes a decisive factor in realizing the promised productivity gains. Fragmented data architectures can slow deployment and dilute the return on automation investments. Third, the talent equation is reshaping procurement and deployment strategies. Persistent shortages of skilled drill operators in isolated mining and energy locations are pushing organizations toward continuous, automated operations, yet integrating these systems requires new competencies in remote supervision, maintenance, and data interpretation. Companies that treat autonomy as a standalone equipment purchase often underestimate the change-management and training requirements that determine long-term adoption success.
Key Drivers Reshaping the Autonomous Drilling Landscape
Technological innovation remains the central catalyst, but the nature of the advancement is evolving from isolated automation features to integrated, fleet-capable intelligence. Modern autonomous drill rigs increasingly rely on advanced sensor fusion, high-resolution positioning, and AI-driven algorithms that provide real-time geotechnical feedback and obstacle detection. These components enable machines to adjust drilling parameters on the fly, maintain consistent hole quality, and operate with minimal human intervention. Recent deployments illustrate how this technology is moving from pilot environments into production settings. A collaborative effort between a leading tool brand and an autonomous mobile robot specialist introduced a downward-drilling, fleet-capable concrete drilling robot designed for data center construction. Pilot programs demonstrated high accuracy across tens of thousands of holes, signaling that autonomous precision is now viable for large-scale floor preparation where consistency and speed directly affect downstream construction schedules. In parallel, mining equipment manufacturers have advanced autonomous surface drilling systems that combine fleet management with real-time optimization, while others have introduced electric autonomous variants and collaborative automation projects targeting fully autonomous face drilling and boom recovery functions. These developments show a clear trajectory: autonomy is being embedded into the core operating logic of the rig, not bolted on as an add-on module. Policy and regulatory momentum is reinforcing this technological shift. Safety mandates and industry standards are increasingly emphasizing the reduction of human exposure to hazardous environments, creating a regulatory tailwind for zero-entry or reduced-entry drilling operations. In mining, autonomous drilling systems align with broader safety objectives by keeping personnel away from active drilling faces and heavy equipment movement zones. In energy and infrastructure, automation is being evaluated not only for efficiency but also for consistency, documentation, and risk mitigation across complex well construction and foundation work. Public and private funding initiatives are also accelerating the maturation of adaptive automation and advanced recovery functions, particularly in academic and industry partnerships that focus on refining autonomous behaviors in variable ground conditions. This combination of safety-driven policy and targeted research support is helping lower the practical barriers to broader deployment. Demand-side behavior is changing as well, driven by project complexity and workforce constraints. The rapid global expansion of data center construction is creating a surge in demand for precise, repeatable floor preparation work, where autonomous concrete drilling robots can accelerate progress while improving accuracy and safety. At the same time, labor shortages and the difficulty of attracting and retaining skilled operators in remote mining locations are encouraging organizations to pursue continuous operations enabled by autonomous drilling technologies. This is not simply a cost equation; it is an operational resilience strategy. Companies are increasingly evaluating autonomy as a way to stabilize production, reduce variability, and maintain output when skilled labor is scarce or difficult to deploy. As a result, demand is spreading beyond traditional reserves into aggregates, quarries, and infrastructure projects where consistent performance and reduced operational risk justify the investment. Supply chain and cost structure dynamics are influencing how quickly organizations can adopt autonomous systems. The reliance on sophisticated sensors, high-resolution positioning hardware, and AI-based control software means that component availability, integration expertise, and software lifecycle management are becoming strategic considerations. Cost structures are also shifting as electric and autonomous variants gain traction, changing the calculus around fuel consumption, maintenance intervals, and emissions compliance. For many operators, the business case increasingly hinges on total cost of ownership over the life of the equipment rather than upfront purchase price. This favors suppliers that can offer integrated solutions, predictable software updates, and service models aligned with continuous, remote-operated workflows. As supply chains for advanced electronics and precision components stabilize and scale, the economics of autonomous drilling are expected to improve further, broadening access beyond early-adopter segments.
Competitive Landscape and Leadership Strategies
The competitive environment is defined by a mix of established equipment manufacturers, energy services companies, and specialized robotics developers, with a meaningful concentration of market share among a limited group of leaders. Incumbents in mining equipment have built strong positions by offering autonomous-ready drill rigs and surface drilling automation platforms that integrate fleet management and real-time optimization. Their advantage lies in decades of domain expertise, extensive field service networks, and the ability to embed autonomy into familiar rig architectures. Recent activity underscores this strategy: one manufacturer delivered an autonomous-ready rotary drill rig to a copper operation and partnered to implement surface drilling automation, while another secured a large order for autonomous and electric blasthole drill rigs in Africa, to be operated fully autonomously with zero exhaust emissions. These moves highlight a dual focus on performance and sustainability, as well as a willingness to commit to large-scale deployments in demanding environments. Energy services companies are pursuing a different but complementary angle, emphasizing drill automation software, directional drilling consistency, and integrated workflows across rig types. Their offerings target the repeatability and precision required in well construction, often pairing automation with geosteering and operational analytics. By focusing on software-defined drilling and service-integrated automation, these players are positioning autonomy as a way to reduce variability in complex wells and improve consistency across campaigns. This software-centric approach expands the definition of autonomous drilling beyond hardware, creating opportunities for companies that can orchestrate data, drilling parameters, and field execution in a unified workflow. A notable dynamic in the landscape is the emergence of specialized robotics and automation collaborators that bring new capabilities into established application areas. A robotics company focused on autonomous mobile platforms and fleet orchestration has partnered to power a downward-drilling concrete robot designed for data center construction, achieving high accuracy in pilot programs and targeting commercial availability in the near term. Another specialist has developed autonomous reverse circulation drill rigs for mining and exploration, with a clear emphasis on removing operators from hazardous manual operations. These entrants illustrate how the market is being shaped not only by traditional equipment rivalry but also by cross-industry partnerships that combine drilling expertise with advanced robotics, fleet management, and application-specific engineering. The result is a more pluralistic competitive field in which differentiation comes from application fit, integration depth, and the ability to deliver measurable accuracy and productivity gains. Market structure appears to be evolving along several axes simultaneously. Consolidation remains a plausible path as larger players seek to broaden their automation portfolios through acquisitions or strategic partnerships, particularly in software, sensing, and fleet orchestration. At the same time, segmentation is intensifying, with companies increasingly specializing by application, region, or level of autonomy. Some competitors are focusing on fully autonomous systems for defined use cases, while others continue to advance semi-autonomous solutions that offer incremental automation for organizations not yet ready for full removal of human operators. New entrants are gaining traction where they can solve a specific operational pain point with a clearly demonstrated accuracy or safety benefit, especially in construction and infrastructure segments that have historically seen less drilling automation. The most successful players are those that can articulate a clear path from installation to sustained operational value, supported by service, training, and data-driven optimization.
Future Trends and Commercial Implications
Over the next three to five years, one of the most consequential trends will be the shift from standalone autonomous rigs to coordinated, fleet-level automation. As more operations deploy multiple automated drill units, the value proposition will increasingly depend on orchestration, task allocation, and centralized monitoring rather than the capabilities of any single machine. Organizations that invest early in data standards, interoperable control architectures, and remote supervision capabilities are likely to extract more value from their automation investments and adapt more quickly as fleets expand. A second trend is the broadening of autonomy beyond traditional mining and energy applications into construction and infrastructure, particularly where precision, repeatability, and labor constraints intersect. Data center construction and large-scale floor preparation are already illustrating how autonomous concrete drilling can improve accuracy and throughput in high-volume projects. This application expansion opens commercial opportunities for suppliers that can tailor autonomy to different substrate conditions, site layouts, and project schedules, while also creating new demand for integration with broader construction workflows. A third trend is the continued coupling of autonomy with electrification and emissions reduction goals, especially in regions and sectors where sustainability requirements and operating costs are moving in tandem. Electric autonomous drill rigs and zero-emission operation concepts are gaining visibility in mining and quarry settings, and this convergence is likely to influence procurement criteria, site planning, and vendor selection. Companies that can offer autonomous performance alongside favorable emissions profiles may find stronger positioning in tenders and long-term partnerships. These trends carry commercial opportunities, but also uncertainty. Adoption velocity will depend on how quickly integration challenges are resolved, how consistently accuracy and reliability hold up across diverse site conditions, and whether organizations can build the internal capabilities needed to manage automated fleets. Economic fluctuations, changes in project pipelines, and evolving safety or emissions regulations could also alter deployment timelines. The most resilient strategies will treat autonomy as a long-term operating model transformation, not a one-time equipment upgrade.
Strategic Recommendations for Decision-Makers
For manufacturers and technology providers, the priority is to deepen application-specific value rather than compete solely on automation features. Differentiation will increasingly come from proven accuracy, fleet orchestration, service and software support, and the ability to demonstrate measurable improvements in safety, consistency, and throughput. Investing in interoperability, remote supervision tools, and clear upgrade paths can help products remain relevant as operations scale from single-rig deployments to coordinated fleets. Partnerships that combine drilling domain expertise with robotics, AI, and fleet management capabilities are likely to accelerate time to value and expand addressable use cases. For investors, the opportunity set is expanding but unevenly distributed. Segments with clear labor constraints, strong safety mandates, and high-volume precision requirements are showing particularly strong adoption logic, while broader market growth will depend on how quickly integration and standardization issues are resolved. Evaluating companies on their ability to deliver total cost of ownership benefits, sustain software and service ecosystems, and expand into adjacent applications can provide a more reliable basis for assessing long-term positioning than headline automation claims alone. For procurement and operations leaders, the practical starting point is to align autonomy investments with operational priorities and site realities. Assessing where autonomy can reduce risk exposure, stabilize output, and improve repeatability should come before technology selection. Pilots should be structured to measure accuracy, downtime, maintenance demands, and supervisory workload, with attention to data integration and training requirements. Building internal capability for remote operation, analytics, and preventive maintenance will be as important as selecting the right equipment. Detailed segmentation data, company-level benchmarks, and application-specific deployment considerations can help translate these strategic themes into precise planning assumptions. For decision-makers seeking a deeper view of market sizing, regional dynamics, and vendor positioning, the full PW Consulting research report provides expanded detail and customizable analysis to support investment, procurement, and product strategy decisions.
PW Consulting
Directional Drilling Market
Worldwide Underwater Dredging Robot Market
For detailed analysis of this topic, please visit the official page: Worldwide Autonomous Drilling Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Market Intelligence: Strategic Trends in the Worldwide Receiving Optical Sub-Assembly Components Market
Market Snapshot: Scale, Momentum, and Structural Headwinds
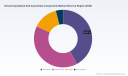
The worldwide market for receiving optical sub-assembly (ROSA) components has transitioned from a specialized supplier niche into a foundational pillar of modern optical communications infrastructure. Valued at approximately $4.58 billion in 2025, the sector has expanded consistently from $2.45 billion in 2020, reflecting a compound annual growth rate of 13.48 percent through the forecast horizon extending to 2032. This trajectory underscores how rapidly receiver sub-assemblies have evolved from peripheral transceiver components to critical enablers of bandwidth scaling, low-latency connectivity, and energy-efficient data transmission. The market's expansion is not merely cyclical; it is structurally reinforced by the parallel growth of optical transceiver volumes, the migration toward coherent and direct-detection architectures at higher data rates, and the continuous densification of fiber-based networks across enterprise, carrier, and cloud environments.
Despite this robust headline growth, the industry is navigating a series of inflection points that will determine margin trajectories, supply chain resilience, and competitive positioning over the next several years. First, the rapid escalation of AI-driven data center workloads is compressing procurement cycles and demanding receiver components that deliver higher sensitivity, broader bandwidth, and tighter integration with transceiver packaging. Traditional ROSA designs optimized for legacy metro or access networks are increasingly misaligned with the performance and form-factor expectations of next-generation optical engines, forcing manufacturers to accelerate material science and packaging innovation while managing yield and cost constraints. Second, geopolitical decoupling and export controls around III-V compound materials and semiconductor manufacturing equipment are reshaping sourcing strategies. Producers reliant on concentrated substrate supply or legacy assembly footprints are encountering longer lead times, pricing volatility, and heightened compliance complexity, making supply chain diversification and regional capacity planning strategic imperatives rather than operational afterthoughts.
Third, the market is experiencing a performance-versus-cost tension that is redefining procurement behavior. As hyperscale operators and system integrators push for lower cost-per-bit and improved power efficiency, receiver suppliers must balance advanced photodiode architectures, amplifier integration, and precision optical alignment against aggressive margin expectations. This dynamic is simultaneously rewarding manufacturers with differentiated process capabilities and pressuring those locked into commoditized assembly models. The net effect is a market that is expanding rapidly in absolute terms but increasingly bifurcated in terms of value capture, where technological readiness, materials access, and integration sophistication determine which players can sustain premium positioning.
Key Drivers Reshaping the Receiving Optical Sub-Assembly Landscape
Technological Innovation and Architectural Shifts
The most immediate driver of market evolution is the convergence of higher data rates, tighter integration, and advanced packaging formats. Receiver sub-assemblies are no longer standalone optical-to-electrical conversion modules; they are increasingly co-designed with transceiver engines, leveraging chip-scale packaging, low-loss optical alignment, and embedded control functionality to meet the latency and power constraints of AI fabric interconnects and high-speed data center links. Innovations in PIN and avalanche photodiode architectures continue to expand the sensitivity and bandwidth envelope, enabling receivers to support emerging modulation formats and extended reach requirements without excessive digital signal processing overhead. At the same time, packaging techniques that improve thermal stability, reduce optical loss, and streamline assembly flow are becoming critical differentiators, allowing suppliers to deliver higher performance within tighter cost and size constraints. Companies that have introduced symmetric, lower-cost chipset approaches and integrated optical sub-assembly optics into broader network solutions illustrate how product portfolios are shifting from discrete component delivery to system-level value creation. Recognition of highly integrated chip-scale packaging and optical sub-assembly products for AI network applications further confirms that the industry is prioritizing compactness, scalability, and performance density over traditional discrete assembly paradigms.
Optical Transceivers Market
Policy, Funding, and Supply Chain Reshaping
Policy momentum is rewriting the geographic and operational calculus for ROSA suppliers. Strategic semiconductor funding initiatives are actively supporting the expansion of indium phosphide substrate and epitaxial wafer production, with investments targeting domestic capacity for lasers and photodetectors used in optical components. These programs are designed to strengthen supply chain resilience for critical optical materials and reduce dependence on concentrated sourcing models. Simultaneously, large-scale equipment orders for metal-organic chemical vapor deposition and related epitaxy systems from leading optical communications manufacturers signal a deliberate ramp in production capability for indium phosphide-based components tied to datacom optical assemblies. The combination of public funding, private capital deployment, and capacity expansion is gradually rewiring the upstream materials landscape, giving qualified suppliers access to more stable substrate pipelines while raising the barrier to entry for manufacturers lacking secure material relationships. However, ongoing export controls and tariff measures on critical materials and semiconductor equipment continue to inject complexity into cross-border sourcing, requiring players to maintain flexible qualification pathways and multi-region supplier strategies to avoid disruption.
Demand-Side Transformation Across Applications
Demand growth is increasingly anchored by application environments that prioritize throughput, reliability, and total cost of ownership. Data center expansion remains a dominant force, driven by cloud infrastructure scaling, AI training and inference clusters, and the need for high-density optical connectivity that can sustain bandwidth growth without proportional increases in power or footprint. Telecommunication networks are undergoing a parallel transformation, with carriers modernizing passive optical networks and metro backbones to support faster broadband delivery, lower latency, and more flexible service architectures. The emergence of chipset solutions designed for next-generation fiber-to-the-room and fiber-to-the-home architectures highlights how receiver sub-assembly design is being aligned with network-level cost reduction goals while preserving performance. Beyond carrier and cloud use cases, enterprise and industrial deployments are contributing incremental but strategically valuable demand, particularly where ruggedized optical links, precise analog reception, and low-noise operation are required for video distribution, voice infrastructure, and specialized sensing applications. Across these segments, buyers are increasingly evaluating receiver components not merely by optical performance specifications but by integration readiness, supply continuity, and lifecycle support, shifting procurement from transactional purchasing to relationship-driven sourcing.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The ROSA market remains moderately concentrated, with a handful of established players commanding meaningful share while a broader field of specialized manufacturers competes on performance, cost, and regional proximity. Leading organizations have built differentiation through a combination of proprietary packaging technologies, photodiode architecture expertise, and application-specific module configurations. Semtech Corporation has reinforced its position by combining receiver sub-assembly optics with broader chipset portfolios that target symmetric fiber architectures and cost-sensitive network deployments, demonstrating a strategy that extends beyond component sales into system-level economics. Eoptolink Technology Inc. has focused on scalable production of transmitter and receiver assemblies alongside indium gallium arsenide photodiodes tailored for digital data applications, emphasizing the ability to move from trial samples to volume manufacturing. Applied Optoelectronics, Inc. continues to supply receiver sub-assemblies across telecom, datacom, and sensing contexts, leveraging broad transceiver integration experience to address multiple end markets with a common technology foundation.
Vitex LLC competes on high-sensitivity photodiodes designed for precise optical-to-electrical conversion, an approach that aligns well with applications where signal integrity and noise performance are paramount. MACOM Technology Solutions has pushed toward high-speed receiver modules with avalanche and PIN photodiodes configured for bandwidth-intensive datacom and telecom requirements, positioning itself in the upper performance tier where speed and package flexibility matter. Agiltron Inc. emphasizes a transceiver platform that balances low cost and high bandwidth for indium gallium arsenide and silicon receiver configurations, appealing to cost-conscious deployments that still require dependable performance. In Asia, Liverage Technology Inc. has maintained a broad speed range covering receiver modules used in 5G, data center, and telecom environments, with both PIN and avalanche variants supporting diverse link budgets. Xiamen San-U Optronics Co., Ltd. has targeted specific form factors and sensitivity profiles for fiber optic applications, an approach that enables focused differentiation in niche receiver segments. Lasermate Group, Inc. integrates photodiodes and amplifiers within its broader fiber optical component portfolio, while EZconn Corporation emphasizes indium gallium arsenide PIN photodiodes for high-speed, low-noise analog use cases in voice, video, and fiber-to-the-home receivers.
The competitive trajectory is shifting from pure specification competition toward integration advantage and supply chain reliability. Market leaders are increasingly rewarded for package-level innovation, co-engineering with transceiver developers, and the ability to support rapid scaling without sacrificing yield. At the same time, recent recognition of highly integrated chip-scale packaging and optical sub-assembly products for AI networks indicates that design integration is becoming a new differentiator, particularly for machine-to-machine and high-performance compute interconnects. The broader pattern points to consolidation among suppliers that can secure stable indium phosphide materials access, advanced packaging capability, and multi-application qualification, while smaller players must either specialize in cost-optimized volume segments or carve out technical niches where sensitivity, bandwidth, or application fit provide defensible margins. New entrants face a steep learning curve because receiver performance depends on tight control over epitaxy, alignment, and packaging, but targeted innovation in chip-scale integration or application-specific receiver configurations can still open viable pathways in high-growth sub-markets.
Optical Circuit Switches Ocs Market
Forward Outlook: Trajectory, Opportunities, and Uncertainty
Over the next three to five years, the receiving optical sub-assembly market is likely to be defined by three interrelated trends. The first is the deepening integration of receiver components into optical engines and co-packaged architectures, driven by the need to reduce power, shrink form factors, and simplify interconnect design for AI and data center networks. Suppliers that can deliver receiver sub-assemblies with chip-scale compatibility, low-loss optical paths, and scalable manufacturing will be best positioned to capture value as transceiver architectures become more tightly coupled. The second trend is the gradual rebalancing of indium phosphide substrate and epitaxy capacity, supported by both public funding and private equipment investment. As domestic and regional production expands, supply chain volatility should moderate for qualified buyers, though pricing and allocation dynamics will remain sensitive to equipment lead times, yield ramp rates, and geopolitical trade conditions. The third trend is the continued bifurcation between performance-premium and cost-optimized receiver segments. High-speed, high-sensitivity, and integrated amplifier solutions will sustain margins in datacom and advanced telecom applications, while volume access, enterprise, and industrial deployments will reward suppliers capable of delivering dependable performance at competitive cost.
PW Consulting
These trends create tangible commercial opportunities. Manufacturers that align product roadmaps with AI-era interconnect requirements, invest in packaging and alignment processes that improve yield and repeatability, and build multi-source material strategies will have stronger negotiating leverage with system integrators and cloud operators. Investors should monitor companies with demonstrable access to indium phosphide substrate pipelines, expanding epitaxy or packaging capacity, and product lines tied to chip-scale or highly integrated optical engines, as these capabilities are increasingly correlated with long-term relevance. Procurement teams, meanwhile, will benefit from developing supplier relationships that extend beyond unit pricing to include qualification support, ramp predictability, and resilience against material or equipment constraints. The principal uncertainties are execution risk in capacity expansions, the pace at which export controls and trade policy might alter materials availability, and the possibility that rapid transceiver architecture shifts could change receiver integration requirements faster than suppliers can adapt. Markets that grow at double-digit rates can still produce uneven outcomes if technology transitions outpace process maturity or if supply chain re-engineering introduces unexpected delays.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align receiver roadmaps with where performance, packaging, and materials access converge most favorably. Investments in chip-scale compatibility, high-sensitivity photodiode variants, and process controls that improve yield and repeatability will be more valuable than incremental specification upgrades alone. Companies should also stress-test supplier relationships for indium phosphide substrates and epitaxy capacity, and qualify alternative sourcing where feasible to reduce exposure to concentrated material dependencies. Building application-specific receiver configurations for AI network interconnects, high-speed data center links, and modernized fiber access networks can open differentiated positioning without requiring platform-wide redesigns.
For investors, the most informative signals will come from capacity deployment, materials access, and integration strategy rather than headline growth alone. Companies with confirmed equipment orders for epitaxy systems, expanding domestic or regional indium phosphide production, and product portfolios tied to highly integrated optical engines warrant closer scrutiny, particularly when paired with demonstrated volume ramp capability. Equally important is assessing whether a player’s differentiation rests on proprietary process knowledge or on interchangeable assembly economics, since the latter tends to erode faster in competitive segments. Portfolio exposure should favor organizations that can translate materials and packaging advantages into recurring transceiver-related demand.
For procurement and supply chain leaders, the strategic shift is from price-only sourcing to resilience-weighted evaluation. Receiver components increasingly influence system-level power, latency, and integration complexity, which means qualification criteria should weigh performance stability, ramp predictability, packaging maturity, and continuity of critical materials. Developing multi-region supplier options and securing early engagement with vendors that are expanding InP-related capacity can reduce vulnerability to allocation shocks or trade-related disruption. For organizations that require deeper segmentation data, scenario modeling, or customized sourcing and investment guidance, a dedicated report provides the granular breakdowns and bespoke analysis needed to translate these market-level signals into operational decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Resceiving Optical Sub-Assembley Components Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Worldwide LED Panel Lights Market
Market Landscape and Core Challenges
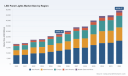
The global LED panel lights market has matured into a multi-billion-dollar segment, with revenue climbing from approximately USD 18.5 billion in 2020 to an estimated USD 27.9 billion by 2025. The trajectory reflects sustained cumulative growth of over 50% across the five-year span, driven by structural replacements of legacy fluorescent and high-intensity discharge fixtures in both commercial and residential settings. Looking ahead, the market is projected to expand from roughly USD 30.5 billion in 2026 toward USD 49.3 billion by 2032, sustaining a compound annual growth rate near 8.5% through the forecast period. This expansion is not merely a continuation of replacement cycles; it signals an inflection point where lighting transitions from a purely utilitarian component to a platform for energy optimization, space reconfiguration, and human-centric environment design.
Several structural challenges are reshaping how participants navigate the next phase of growth. First, regulatory efficacy thresholds are tightening globally, forcing manufacturers to reconcile performance requirements with cost constraints and design trade-offs. As standards evolve, products that once qualified as efficient are being outclassed by newer benchmarks, pushing continuous R&D investment and rendering legacy SKUs obsolete faster than in prior cycles. Second, the supply chain for key semiconductor and rare-earth materials remains exposed to geopolitical friction and licensing adjustments. Export controls and tariff frameworks affecting gallium, germanium, and certain processed critical minerals have introduced intermittent cost volatility and sourcing complexity, particularly for manufacturers reliant on specific regional component pipelines. Third, price compression in LED chips and core components continues to reshape margin dynamics. Capacity expansions and the transition to larger wafer formats have lowered input costs, but they simultaneously intensify competition on price, shifting the battleground toward differentiation in optics, controls integration, and application-specific engineering rather than raw lumen output alone.
The market also exhibits moderate concentration, with the top three firms capturing roughly 18.5% of revenue and the top five approaching 28.4%. This fragmented yet increasingly consolidated structure indicates that scale advantages exist, but regional expertise, application specialization, and channel relationships still determine competitive outcomes in many geographies. For decision-makers, the central challenge is to balance volume efficiency with the innovation required to stay ahead of tightening standards and shifting buyer expectations.
Key Drivers of Market Change
Technological Innovation and Performance Breakpoints
Advances in LED chip architecture, thermal management, and optical extraction are redefining what a panel light can deliver. The shift toward higher-efficacy packages and improved luminaire-level designs is enabling installations that meet tighter energy codes while reducing the number of fixtures needed for a given illuminance target. Manufacturers are increasingly building panels with tunable-white capabilities, enhanced glare control, and integrated sensing or communication features, transforming the product from a static light source into an active component of smart building ecosystems. These capabilities matter commercially because they allow facility operators to align lighting with occupancy patterns, daylight availability, and wellness objectives without separate retrofit hardware.
Policy and Regulatory Momentum
Government and standards-body initiatives continue to accelerate adoption by raising minimum performance bars and incentivizing commercial retrofits. Updated efficacy requirements for solid-state lighting took effect in early 2026, raising minimum thresholds across categories by roughly 14% and effectively resetting the baseline for compliant products. Alongside these mandates, public and utility-led programs continue to support energy-efficient upgrades in offices, institutions, and industrial facilities. The practical effect is twofold: buyers face stronger reasons to replace aging fixtures now rather than defer upgrades, and suppliers must ensure their portfolios meet or exceed revised benchmarks to remain eligible for incentive-driven procurement.
Demand-Side Behavior Shifts
Buyers are increasingly evaluating lighting as part of a broader total-cost-of-ownership calculation rather than as a standalone commodity. Commercial operators prioritize long lifespans, maintenance reductions, and compatibility with building management systems. Healthcare and institutional purchasers focus on visual comfort, circadian-supportive tuning, and reliable performance in sensitive environments. Residential demand, while smaller in absolute revenue contribution, is growing as homeowners and multi-family developers standardize on flat-panel forms for renovation and new construction, especially where ceiling heights and aesthetic preferences favor low-profile solutions. This diversified demand mix encourages manufacturers to tailor product lines rather than push a uniform offering across segments.
Supply Chain and Cost Structure Evolution
On the input side, the LED component market has experienced sustained price compression as capacity expands and manufacturers transition to larger wafer formats such as 8-inch GaN-on-Si. This shift supports lower assembly costs and enables more aggressive pricing in volume segments. At the same time, sourcing of critical materials remains sensitive to trade policy and licensing conditions, creating pockets of uncertainty for product lines heavily dependent on specific raw-material pathways. The net result is a market where cost advantages from components can be partially offset by geopolitical and logistics variability, reinforcing the value of diversified sourcing and forward hedging for larger producers. Recent trade-show presentations have highlighted energy efficiency and human-centric design as recurring themes, reflecting how suppliers are positioning these cost and performance dynamics as competitive differentiators.
Competitive Landscape and Leading Strategies
The competitive field includes established global players with broad portfolios and strong channel presence, alongside regional manufacturers that compete on price, responsiveness, and localized application support. Global leaders with heritage in lighting and component systems emphasize integrated smart controls, high efficacy, and application-optimized designs for offices, retail, and institutional environments. These firms often leverage brand trust, regulatory-compliance track records, and building-system integration capabilities to secure large commercial accounts. Component-oriented suppliers contribute high-performance LED modules and finished panels focused on reliability and commercial/industrial use, while North American manufacturers have built strong positions through established brand portfolios tailored to commercial, institutional, and architectural specifications.
LED Grow Lights Market
In the premium tier, some participants differentiate through advanced optics, tunable white, and human-centric lighting features, targeting architects and design-led projects where visual quality and flexibility carry premium value. Other manufacturers concentrate on energy-efficient solutions for both commercial and residential markets, emphasizing quality, longevity, and integration with building systems. Large industrial and electrical groups extend their reach through dedicated lighting portfolios that serve commercial, industrial, and hazardous-location applications, using existing distribution relationships and engineering support networks to win specification work. In Asia and export markets, cost-effective and mid-tier manufacturers have expanded their footprint by combining affordable pricing with broad product ranges, and specialized producers have carved out niches with customizable high-lumen panels, dimming options, and certification-ready configurations for commercial projects. Others focus on ceiling panel lights and linear systems for architectural and commercial work, maintaining visibility through trade-show participation and international distribution.
The landscape is evolving through a mix of consolidation and differentiation. Larger incumbents are strengthening portfolios through brand breadth, controls integration, and reliability credentials, while regional players compete by aligning product specifications closely with local code requirements, price sensitivity, and application needs. New entrants tend to succeed when they address specific gaps rather than attempting head-on competition across the entire spectrum. Recent market activity illustrates how firms are positioning themselves: one manufacturer emphasized energy efficiency and human-centric design in panel and linear solutions at a major Frankfurt fair, signaling an industry-wide pivot toward performance-plus-wellness narratives. Simultaneously, updated technical requirements for solid-state lighting raised efficacy thresholds by approximately 14%, compelling portfolio upgrades and creating a natural filter that favors suppliers with stronger R&D and faster compliance cycles. For buyers, the implication is that specification value increasingly resides in verified performance, interoperability, and documentation quality, not just initial price.
Future Outlook: Three Trends Shaping the Next 3–5 Years
The first trend is mainstream human-centric and tunable lighting. As circadian-supportive features and daylight-aligned tuning move from niche to standard expectations in commercial, healthcare, and higher-end residential projects, manufacturers that can deliver reliable color consistency, intuitive controls, and documented visual-comfort benefits will capture premium specifications. The commercial opportunity lies in bundled offerings that pair panels with sensing, scheduling, and integration tools, reducing the need for separate retrofit layers.
The second trend is controls and interoperability as a core product attribute rather than an add-on. Building operators increasingly want lighting that communicates with energy-management platforms, occupancy sensors, and daylight-harvesting systems. Products designed from the outset for interoperability will gain preference in specification work, particularly where efficiency mandates and operational cost pressures make integrated automation attractive. The opportunity is to streamline commissioning and data visibility so that lighting contributes measurable savings and maintenance intelligence.
The third trend is regional diversification of supply and product strategy. Given continued sensitivity around critical materials and shifting trade frameworks, participants are likely to expand multi-source procurement, adjust regional assembly footprints, and tailor portfolios to local code trajectories. For manufacturers, this creates opportunities in application-specific designs and localized compliance documentation. For buyers, it rewards suppliers with transparent sourcing and resilient delivery models. The principal risk is that tighter standards and material constraints could compress margins for undifferentiated products, while rapid product cycles may challenge inventory planning if demand shifts faster than forecasts anticipate.
PW Consulting
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to align product roadmaps with revised efficacy benchmarks and application-specific value propositions. Investing in optics, thermal design, and controls-ready architectures will protect eligibility for incentive-driven commercial work and support premium positioning where visual quality and wellbeing matter. Diversifying component sourcing and locking in compliant SKU transitions will reduce exposure to material and regulatory friction.
For investors, the most durable opportunities sit with suppliers that combine verified performance, interoperability, and regional execution capability. Preference should be given to businesses that can demonstrate repeatable compliance, clear differentiation beyond price, and the ability to serve both broad commercial accounts and specialized application niches. Monitoring portfolio refresh cycles and certification readiness is a useful leading indicator of resilience.
OLED Lighting Panels Market
For procurement and specification teams, the practical value lies in evaluating total cost of ownership, including energy performance, maintenance intervals, and integration effort, rather than minimizing upfront unit price. Verifying documentation, interoperability claims, and warranty terms will reduce long-term operational risk. Given the pace of regulatory change and portfolio evolution, maintaining access to detailed segment-level data and tailored procurement guidance can materially improve specification choices and budget planning, particularly when projects span multiple codes and application requirements.
Detailed breakdowns by region, product type, application, and competitive positioning can help translate these market-level dynamics into project-level decisions. Comprehensive research covering submarket sizes, adoption trajectories, and company-specific positioning is available for teams that need granular inputs for budgeting, sourcing, and strategic planning.
For detailed analysis of this topic, please visit the official page: Worldwide LED Panel Lights Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Medical Beauty Hyaluronic Acid Injection Market: 9.4% CAGR and Strategic Shifts Redefining Global Growth
By pmarketresearch, 2026-09-18
The Worldwide Medical Beauty Hyaluronic Acid Injection Market: Strategic Trends and Commercial Opportunities
At $6.45 billion in 2025, the global medical beauty hyaluronic acid injection market has transitioned from a niche aesthetic niche to a core pillar of the broader wellness and anti-aging economy. Over the past five years, steady expansion has been driven by rising disposable incomes, aging demographics, and the normalization of minimally invasive procedures. Forward projections indicate the market will approach $12.08 billion by 2032, reflecting a compound annual growth rate of 9.38 percent. This trajectory signals sustained demand, but it also underscores a landscape that is maturing rapidly. Growth is no longer solely a function of volume; it is increasingly shaped by product differentiation, regulatory navigation, and the ability to balance clinical performance with patient expectations. For executives and investors, the next phase will reward those who can read structural shifts rather than simply track headline numbers.
Navigating the Current Landscape: Scale, Shifts, and Pressures
The market today operates at a scale that commands strategic attention across multiple geographies and business models. Growth has been broad-based, but the composition of that growth is uneven. Regions with established aesthetic treatment cultures continue to anchor demand, while emerging markets are accelerating adoption through expanding clinic networks, rising middle-class spending, and greater access to trained practitioners. At the same time, the competitive field is consolidating around a small group of companies that collectively hold a majority share of the market. This concentration reflects the capital intensity of development, the importance of regulatory track records, and the value of established distribution relationships. Yet concentration does not guarantee uniform success; it raises the bar for differentiation and operational execution.
Three structural pressures are reshaping how companies compete and how purchasers evaluate options. First, the distinction between clinical credibility and aesthetic preference is narrowing. Patients and providers increasingly expect injectables that deliver visible results while preserving natural movement and minimizing downtime. Products that cannot articulate a clear positioning around longevity, integration, or dynamic tissue compatibility face margin pressure and substitution risk. Second, regulatory pathways are becoming more granular. Approval in one market does not automatically translate into commercial traction in another, and indications, labeling, and post-market expectations vary enough to affect launch sequencing and inventory strategy. Third, the raw material layer is tightening. Medical-grade hyaluronic acid is no longer a commodity input; pricing dispersion, availability, and quality thresholds are reshaping cost structures and forcing manufacturers to make deliberate choices about sourcing, formulation, and scale.
These pressures are not abstract. They influence pricing power, portfolio design, channel strategy, and the pace at which new entrants can establish a foothold. The market is large enough to absorb multiple winners, but it is also selective enough to marginalize undifferentiated offerings. The companies that thrive will be those that treat these dynamics as design constraints rather than background noise.
Core Drivers Reshaping the Market
Several forces are converging to redefine growth patterns and competitive advantage. The first is technical innovation in product architecture. The industry is moving beyond volume restoration alone toward formulations engineered for specific tissue environments and treatment goals. Differences in crosslinking, particle characteristics, and rheological behavior are increasingly used to signal fit for distinct clinical scenarios, from deep structural support to fine line correction and dynamic facial areas. This evolution is visible in how leading portfolios are positioned and in the scientific discourse at major aesthetic congresses, where manufacturers are emphasizing natural movement, integration, and long-term performance as key value propositions. The strategic implication is clear: innovation is shifting from broad claims to targeted clinical utility, and that shift changes how products are priced, prescribed, and adopted.
PW Consulting
The second driver is the regulatory and approval environment. Approval momentum has broadened the menu of available options and expanded the set of treatable indications. Recent approvals have included new hyaluronic acid gels for dynamic wrinkles and folds, as well as expanded indications for existing products in areas such as temple hollowing and infraorbital hollow. These developments matter because they do more than add SKUs; they alter treatment protocols, support practitioner education, and create new commercial pathways. For manufacturers, regulatory progress can unlock revenue faster than product development alone, but it also requires disciplined launch execution and clear communication around appropriate use. For clinics and buyers, a wider approved set of products can improve access and choice, while also increasing the need for training and protocol alignment.
The third driver is demand-side behavior. The consumer base has become more informed and more selective. Patients are comparing outcomes, longevity, downtime, and provider expertise rather than treating injectables as interchangeable commodities. This maturity is reinforced by the visibility of treatments on social platforms, the growth of reputable clinic networks, and a broader cultural shift toward preventative and maintenance-oriented aesthetics. For businesses, the implication is that marketing and sales cannot rely on category awareness alone. Differentiation must be supported by clinical data, consistent practitioner experience, and post-procedure credibility. Providers, in turn, are gravitating toward products and platforms that help them manage expectations, reduce complication risk, and maintain repeat demand.
The fourth driver is the supply-side and cost structure, especially around raw materials. Medical-grade hyaluronic acid now spans a wide price range depending on molecular weight, purity, and endotoxin limits, and the underlying raw material market is expanding as demand rises. In parallel, the commercial standard has shifted toward non-animal microbial fermentation-sourced HA for regulated applications, reducing variability and contamination risk but also consolidating the supplier base around manufacturers that can meet stringent quality requirements. This transition has two consequences. It raises the importance of supply reliability and technical control, and it gives an advantage to companies that can stabilize cost inputs while maintaining product performance. For vertically integrated players, raw material capability can become a source of margin resilience. For others, it becomes a negotiation and risk management priority.
Competitive Landscape and Leading Strategies
The market is anchored by a set of established companies that have built recognition around distinct product families, indications, and clinical narratives. AbbVie, through its JUVÉDERM collection, continues to use volume restoration and facial contouring as a foundation while pushing a more advanced narrative around undetectable, natural-looking outcomes in dynamic facial areas. Galderma has reinforced the Restylane portfolio with NASHA and OBT technology and has recently advanced syringe technology across facial and hand indications, improving handling and treatment consistency. Merz markets the Belotero range with an emphasis on integration into facial tissue for moderate to severe wrinkles and folds, while Teoxane has built its RHA collection around resilient formulations designed for natural movement. Each of these players has chosen a different point of emphasis, reflecting the reality that success depends on more than scale alone.
The field also includes companies using regulatory approvals and targeted launches to gain traction. Evolus introduced the Evolysse collection for dynamic facial wrinkles and folds after securing approval, creating an entry point into the U.S. market with a defined clinical focus. Hugel supplies fillers for global aesthetic markets and has continued to expand its international presence. Bloomage and LG Chem represent manufacturers with strong material and product capabilities, while Shanghai Haohai, HTL Biotechnology, and several other suppliers contribute to a broader ecosystem spanning raw material production and finished devices. This mix shows that the market supports both brand-led portfolio strategies and material-focused supply models, depending on capital, regulatory readiness, and geographic ambition.
Latest developments reinforce how competitive dynamics are playing out. At the 2026 Aesthetic & Anti-Aging Medicine World Congress, AbbVie framed the next phase of HA injectables around an “Undetectable Era,” signaling a shift toward outcomes that resist visible overcorrection. Galderma secured approvals across the EU, U.S., and Canada for a new Restylane syringe for use with its NASHA lidocaine range, an operational improvement that can affect clinician adoption and treatment workflow. Separately, Waldencast entered the U.S. market after FDA approval of Obagi saypha MagIQ, and Evolus launched Evolysse Form and Smooth following FDA approval, illustrating how approvals and launches are opening entry points even in a concentrated market. These moves suggest that incumbents are defending share through evolution and that new entrants are pursuing focused, indication-led openings rather than broad disruption.
The landscape is likely to continue splitting between consolidation and specialized entry. Consolidation favors companies that can combine regulatory credibility, distribution reach, and portfolio breadth. But it also creates room for specialized players if they can demonstrate a clear clinical fit, manage supply and quality, and build practitioner trust. The differentiating factors will increasingly be formulation intelligence, indication alignment, delivery experience, and the ability to support training and consistent outcomes. In that environment, broad presence is useful, but precise positioning is decisive.
Forward Outlook: Trends and Commercial Implications
Over the next three to five years, three trends are likely to shape strategy. The first is the continued shift from generalized fillers to indication-specific and movement-aware products. As practitioners become more selective and patients more educated, formulations that align with tissue behavior and treatment zones will gain preference. This creates opportunities for companies that can demonstrate differentiated performance in defined clinical scenarios and that can support training, labeling, and protocol design accordingly.
The second trend is regulatory-driven expansion of usable indications and product formats. As approvals add new treatment areas and as delivery features improve, the addressable use cases will widen. That growth is commercially valuable, but it also introduces complexity in education, inventory planning, and post-market compliance. Businesses that can synchronize product launches with practitioner education and clear usage guidance are more likely to convert approval momentum into sustained adoption.
The third trend is supply-side refinement. As medical-grade HA continues to move toward fermentation-based sourcing and stricter purity standards, procurement resilience and cost discipline will become more important. Companies with stable material access and consistent quality will have an advantage in pricing and launch reliability, especially if raw material pricing remains variable. This also means that vertical integration, long-term supplier relationships, and formulation control will be increasingly strategic rather than optional.
These trends carry both opportunity and risk. Demand appears durable, but growth can be uneven across markets, indications, and provider types. Regulatory success does not guarantee commercial success if launch execution, education, and distribution are weak. And while innovation creates premium positioning potential, over-segmentation can complicate supply and slow scale if portfolios become too fragmented. The most resilient strategies will balance clinical specificity with operational simplicity.
Hyaluronic Acid Market
Strategic Actions for Decision-Makers
For manufacturers and brand owners, the priority is to sharpen product positioning around clear clinical use cases and to align formulation, delivery, and education with those use cases. A focused portfolio that maps to practitioner needs and patient expectations is more likely to defend pricing and build repeat use than an undifferentiated expansion strategy. Equally important is supply resilience: securing predictable access to medical-grade raw materials and maintaining quality control should be treated as a competitive capability, not just a procurement task.
For investors, the opportunity lies in identifying companies with credible regulatory records, defensible formulation or delivery advantages, and realistic launch execution plans. Market growth is strong, but returns will depend on execution quality, concentration dynamics, and the ability to convert approvals into uptake. Due diligence should therefore weigh indication strategy, supply security, and go-to-market discipline as closely as headline market size.
For clinics, procurement teams, and treatment providers, the practical imperative is to standardize evaluation around outcomes, safety, handling, and indication fit rather than price alone. Selecting products that match the intended treatment zone and supporting them with consistent training can reduce variability and improve patient satisfaction. On the purchasing side, building relationships with suppliers that demonstrate quality consistency and launch reliability will help manage supply risk as the market matures.
Hyaluronic Acid Dermal Filler Market
As the market scales toward the $12 billion range by 2032, the strategic edge will belong to organizations that can integrate technical differentiation, regulatory execution, and supply discipline into a coherent commercial model. For decision-makers seeking deeper segmentation data, competitor benchmarks, and tailored planning inputs, the full PW Consulting research report provides the detailed breakdown needed to translate these trends into actionable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Medical Beauty Hyaluronic Acid Injection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Far Infrared Fabric Revolution: Strategic Trends and Commercial Opportunities in a $1.3 Billion Market
Market Overview: Growth Trajectory and Structural Challenges
The global far infrared (FIR) fabric market has evolved from a niche experimental segment into a substantial commercial category, demonstrating consistent expansion over the past half-decade. Valued at approximately $540 million in 2020, the market crossed the $785 million threshold in 2025 and is projected to reach $1.35 billion by 2032, reflecting a compound annual growth rate of roughly 8 percent. This trajectory signals that infrared-integrated textiles are no longer confined to emerging wellness trends but have established themselves as a viable functional material category across multiple consumer and industrial verticals.
Despite this momentum, the sector faces structural friction that separates sustainable growth from speculative hype. One pressing challenge revolves around claim validation and regulatory fragmentation. Far infrared textiles operate through emissivity mechanisms that depend on ceramic nanoparticle integration, mineral compounding, or graphene loading, but translating laboratory emissivity results into reproducible end-user performance remains difficult. Standards such as GB/T 30127-2013 are referenced in select markets, yet buyers encounter divergent certification requirements across regions. A product validated for temporary local circulation support in one jurisdiction may face entirely different claim constraints in another, forcing manufacturers to navigate multiple compliance pathways before scaling commercial rollouts.
A second challenge lies in balancing functional efficacy with cost structures. Graphene-enhanced variants and high-loading ceramic composites typically command price premiums of fifteen to forty percent over conventional performance fabrics. While melt-spinning processes can maintain mechanical stability across more than one hundred fifty wash cycles, achieving that durability requires precise compounding control and consistent polymer integration. Fabricators that underinvest in production discipline risk losing the thermal and circulatory benefits that justify the premium in the first place, eroding customer trust and margin resilience over time.
A third issue concerns market concentration and competitive differentiation. The top three participants collectively account for approximately thirty-two percent of global revenue, while the top five reach just under half of total market value. This distribution indicates a landscape where established players hold meaningful share but still leave considerable room for regional specialists and innovators. The strategic risk for incumbents is complacency in product iteration, while newer entrants must differentiate beyond ingredient marketing and prove that their FIR yarns or finished fabrics deliver measurable benefits in real-world use cases such as active recovery, thermal comfort, or sleep support.
Key Drivers Shaping the FIR Fabric Landscape
Technological Innovation and Material Breakthroughs
Materials science continues to reshape what far infrared textiles can deliver. Ceramic-infused polyester remains the dominant fiber architecture, while carbon and graphene-infused variants and bio-ceramic nylon are expanding the functional envelope. Advances in polymer nanotechnology allow manufacturers to refine mineral powders derived from gemstones, volcanic mud, or engineered ceramics and embed them more uniformly within base fibers during melt-spinning or polymerization. The result is a set of yarns and fabrics that can absorb body heat or ambient energy and re-emit it within the eight-to-twelve micrometer range, supporting perceived improvements in circulation, recovery, and thermal comfort.
Recent commercial activity underscores how material innovation is moving from R&D benches into branded product lines. In April 2025, The LYCRA Company promoted its THERMOLITE® FAR INFRARED technology for socks and legwear, emphasizing lightweight hollow fibers with permanent ceramic pigments designed to harness body infrared energy for gentle warming. This launch intersected with broader retail collaborations involving NEXT jeans and H&M collections featuring related infrared technologies, illustrating how fiber-level innovation is being translated into mainstream apparel categories rather than remaining confined to specialty therapeutic products.
Regulatory Clarity and Claim Environments
The regulatory landscape is increasingly shaping how FIR fabrics are positioned and sold. CELLIANT® infrared technology, for instance, has been determined as a general wellness product and reviewed under the FDA 513(g) process for appropriate claims regarding temporary increase in local circulation in healthy individuals. In parallel, the technology has been designated a Class 1 Medical Device in multiple markets including the EU, Japan, the UK, and Australia, with additional clearance pathways pursued in regions such as China. This layered classification structure creates both opportunity and complexity. Manufacturers that proactively align product claims with recognized regulatory categories can build stronger credibility with retailers, healthcare-adjacent buyers, and performance-focused consumers.
Simultaneously, the emphasis on third-party lab certifications and emissivity testing is becoming a differentiator in buyer evaluation. As markets reference testing protocols such as GB/T 30127-2013 and require documented emissivity performance, suppliers that invest in transparent validation can separate themselves from competitors relying on vague wellness assertions. This shift favors companies capable of supporting marketing narratives with repeatable test data and consistent production quality.
Demand-Side Shifts Across Consumer and Institutional Channels
Demand for far infrared fabrics is expanding through converging consumer and institutional behaviors. Performance-oriented consumers increasingly look for apparel that supports circulation, recovery, and thermal comfort without adding bulk or sacrificing breathability. In healthcare and therapeutic settings, textile buyers are exploring functional fabrics that can complement rest, rehabilitation, and patient comfort protocols. At the same time, home textiles and sleep-focused products are drawing interest from shoppers seeking non-invasive comfort enhancement in bedding and loungewear.
This demand diversification is visible in how manufacturers are broadening their SKU and service offerings. In May 2025, Sportingtex highlighted customizable FIR fabric options with certified technology for sportswear, health tech, and apparel, stressing OEM/ODM capabilities, sustainable production practices, and proven wellness benefits. Earlier catalog activity from other players reflects similar positioning, with FIR yarns being adapted for athletic wear, medical care, pet apparel, equestrian gear, and bedding. The practical implication is clear: FIR fabrics are crossing from single-purpose therapeutic niches into multi-category functional textiles, which expands total addressable demand but also raises the bar for category-specific performance validation.
Worldwide Heated Fabric Market
Supply-Side and Cost Structure Dynamics
Supply chain considerations are becoming more decisive as the market scales. Far infrared fabrics commonly incorporate ceramic nanoparticles, mineral powders, or graphene into polyester or nylon via melt-spinning or polymerization. The quality of this integration directly affects emissivity consistency, wash durability, and end-product cost. Suppliers that master compounding uniformity and process control can maintain mechanical properties across repeated laundering while preserving functional claims, whereas weaker process discipline leads to variability that undermines performance reliability.
Cost structure dynamics are also evolving as premium materials become more embedded in mainstream categories. Graphene-enhanced variants can add a substantial price premium, so commercial success depends on pairing the material upgrade with defensible value: thermal retention in cold-weather apparel, recovery support in activewear, or comfort benefits in sleep and therapeutic products. At the same time, sustainability pressures are encouraging EcoMade variants and resource-efficient manufacturing approaches, which can be leveraged as secondary differentiators when positioned carefully alongside functional performance rather than as standalone marketing claims.
PW Consulting
Competitive Landscape: Positioning, Differentiation, and Evolution
The competitive field in far infrared fabrics is diverse, spanning medical-device-aligned innovators, performance fiber specialists, and regional textile manufacturers with strong OEM/ODM capabilities. Hologenix, LLC, through its CELLIANT® technology, occupies a distinctive position by embedding a proprietary blend of natural minerals into fibers, yarns, and fabrics and by pursuing regulatory recognition across multiple markets. Its status as a Class 1 Medical Device in the EU, Japan, the UK, and other regions provides a credibility anchor, while its focus on performance, recovery, and sleep applications gives it relevance in both wellness and athletic recovery segments.
The LYCRA Company differentiates through THERMOLITE® FAR INFRARED fiber and technology, using lightweight hollow fibers with permanent ceramic pigments to deliver gentle warmth in legwear, socks, hosiery, activewear, denim, and outerwear. Its emphasis on permanent warming performance and sustainability-oriented EcoMade variants reflects a strategy that pairs functional benefits with mainstream apparel compatibility. Hitek Textile Co., Ltd. takes a different approach, specializing in SiTEX® FIR Yarn and related jacquard, lace, and tricot knit fabrics that use over twenty natural minerals refined with polymer nanotechnology for energized resonance effects, while offering patented yarn and OEM/ODM services for global brands.
Regional manufacturers such as NUREL Synthetic Fibers, Sportingtex, Acelon, and FIRBEST Co., Ltd. illustrate how localized expertise can translate into strong category niches. NUREL produces NERIDE FIR PA6 nylon yarn with gemstone mineral additives aimed at sportswear, therapeutic clothing, sleepwear, and cold-weather use. Sportingtex manufactures far infrared thermal fabrics using ceramic nanoparticles with emissivity values in the 0.83–0.92 range, serving sportswear, medical care, petswear, equestrian applications, and bedding. Acelon supplies AceVitality® medical yarn with far-infrared microelements for healthcare, sports, and rehabilitation textiles with antibacterial and FIR benefits, while FIRBEST produces KODENSHI® functional material with patented compounding technology across multiple countries.
Larger industrial players also participate in the space. Hyosung Corporation develops aerogear far-infrared yarn with embedded minerals for blood circulation benefits, combined with moisture management in polyester yarns. RadiciGroup offers Radilon® Enjoy polyamide fabrics with far-infrared emission properties for energy and wellness benefits, and Energy Textiles, LLC manufactures Radiance™ far-infrared textiles using ceramic particles in yarn to recycle body energy and support performance, recovery, and sleep products.
The strategic pattern across leading players is divergence in how they convert material science into commercial trust. Some emphasize regulatory alignment and medical-device-adjacent positioning, others prioritize fiber architecture and wash durability, and still others lean on OEM/ODM agility and application breadth. This fragmentation is likely to evolve in two directions. First, consolidation may accelerate as larger textile and fiber groups seek to internalize FIR capabilities and reduce reliance on single-source specialty suppliers. Second, new entrants may continue to emerge around specific applications such as athletic recovery, sleep comfort, therapeutic textiles, or even pet and equine segments, where narrower use cases allow faster proof-of-value. The winners will be those that combine reproducible emissivity performance, credible claim management, and reliable production scale rather than ingredient novelty alone.
Future Outlook: Trends and Commercial Implications for the Next Three to Five Years
One defining trend over the next several years will be the migration of far infrared fabrics from specialty wellness products toward broader functional textiles with more rigorous claim discipline. As buyers in apparel, home textiles, and therapeutic channels demand third-party validation and repeatable emissivity performance, the market will likely reward suppliers that can standardize testing, documentation, and production controls across SKUs. This creates commercial opportunities for manufacturers that can offer certified, application-specific fabric systems rather than generic “infrared” labels, especially in activewear, sleep products, and medical-adjacent textiles.
A second trend is the increasing layering of functional benefits. Far infrared is rarely evaluated in isolation anymore; it is being combined with moisture management, thermal regulation, antibacterial properties, and sustainability-oriented fiber choices. This convergence opens doorways for differentiated product architectures, such as hollow-fiber warming platforms paired with FIR emissivity, or polyamide systems that blend circulation-support benefits with rehabilitation and cold-weather performance. Companies that design around benefit stacking and category-specific use cases are better positioned to command price premiums without relying solely on raw material cost justification.
A third trend involves geographic and channel expansion, particularly where regulatory pathways and testing practices are becoming more defined. Markets that emphasize emissivity standards and recognize wellness or Class 1 device frameworks can provide faster routes to retail and institutional adoption, while regions with less harmonized claim environments may require longer education cycles. The strategic opportunity lies in matching product positioning to the destination market’s validation expectations early rather than retooling claims after launch. Still, uncertainty remains. Overstatement of health benefits, inconsistent wash durability, and fluctuating raw material costs can all weaken category credibility if not managed carefully. Premium pricing also introduces exposure to consumer sensitivity in cost-conscious segments, meaning that value communication must be precise and evidence-aligned.
Strategic Recommendations for Decision Makers
For manufacturers and fabric developers, the immediate priority is to make emissivity performance and wash durability measurable, repeatable, and transparent across product lines. Investing in compounding control, third-party validation, and application-specific testing will do more to protect margins than expanding ingredient claims. Where premium materials such as graphene or high-loading ceramics are used, the value proposition should be tied to clearly defined benefits in the target application, whether that is thermal warmth in legwear, recovery support in activewear, or comfort in sleep textiles.
For investors, the most attractive opportunities are likely to emerge where companies combine credible regulatory or validation positioning with scalable production and a diversified application base. Pure ingredient novelty is increasingly insufficient; commercial resilience depends on documentation, OEM/ODM flexibility, and the ability to serve multiple channels without diluting performance consistency. Due diligence should therefore focus on testing discipline, claim management, and the durability of differentiating technologies under repeated use and laundering.
For procurement and sourcing teams, the practical move is to evaluate FIR suppliers against reproducibility and compliance readiness rather than marketing language alone. Request emissivity data, wash-cycle performance evidence, and regulatory or certification alignment relevant to the end market. Where customization matters, prioritize partners with proven OEM/ODM capabilities and a track record of maintaining functional properties across batches. Given the pace of product launches, catalog expansions, and regulatory developments across the category, timely access to detailed segmentation data, competitive benchmarks, and market-specific entry information can materially improve sourcing and investment decisions. Readers seeking deeper segmentation detail, company-level comparisons, and region-level market data may find value in the full PW Consulting market report, which provides the supporting structure needed to translate these strategic themes into operational choices.
Worldwide Infrared Massage Therapy Bed Market
For detailed analysis of this topic, please visit the official page: Worldwide Far Infrared Fabric Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
How 24.41% CAGR and 79.2% Concentration Are Redefining the Worldwide Online Audiobook Site Market Through 2032
By pmarketresearch, 2026-09-18
The Worldwide Online Audiobook Site Market: Strategic Trends and Commercial Opportunities
Market Overview: Scale, Momentum, and Structural Challenges
The global online audiobook marketplace has entered a defining growth phase, transitioning from a niche convenience into a mainstream content consumption channel. Between 2020 and 2025, the sector expanded from approximately $3.45 billion to over $10.5 billion in annual revenue, reflecting sustained adoption across consumer and professional segments. The trajectory forward points to continued acceleration, with an expected compound annual growth rate of 24.41% through 2032. By the end of that forecast horizon, the market is projected to surpass $48.4 billion in total annual turnover. This growth is not merely a function of demographic tailwinds or pandemic-era habit formation; it reflects a structural shift in how audiences consume long-form narrative, educational, and reference content across mobility constraints, multitasking lifestyles, and accessibility requirements.
Audiobook Apps Market
Despite the optimism, the market faces several structural inflection points that will determine which operators capture durable value. First, concentration remains high at the platform level. The top three operators command roughly two-thirds of overall platform revenue, while the top five approach eight-tenths of total activity. This concentration creates pricing power and catalog leverage for incumbents, but it also raises barriers for independent publishers and mid-tier platforms seeking distribution reach without sacrificing margin. Second, infrastructure costs are rising in tandem with streaming volumes. Data center electricity consumption tied to digital content delivery has grown substantially in recent years, with U.S. facilities alone accounting for a meaningful share of national power demand and projections pointing toward continued escalation through the end of the decade. Platforms that scale catalog depth and recommendation algorithms without addressing hosting efficiency and edge delivery will face margin compression. Third, regulatory fragmentation is becoming a practical operational constraint rather than a distant compliance issue. An expanding patchwork of state-level privacy frameworks in the United States, alongside established European data protection and operational resilience requirements, forces global platforms to rethink how listening data, user profiles, and payment information are stored, processed, and transferred across jurisdictions. Platforms that treat compliance as a secondary function will encounter friction in expansion, particularly where localization expectations intersect with multi-region content licensing.
These dynamics create a market that is simultaneously expanding and consolidating in practice. Growth is real, but it is increasingly conditional on operational discipline, data governance maturity, and the ability to convert broad catalog access into differentiated user experiences. The next phase of value creation will depend less on raw title count and more on how platforms structure monetization, manage infrastructure spend, and navigate an increasingly layered regulatory environment.
Key Drivers Shaping the Market
Technological Innovation and Listening Experience Design
The most visible driver of market expansion is the transformation of the listening experience itself. Audible has doubled down on catalog depth and ecosystem integration, offering the world’s largest audiobook library and weaving listening into the broader retail and device environment that supports exclusive originals and seamless playback. Spotify has pursued a different technical wedge: embedding audiobooks within an already-scaled music and podcast subscription, supplemented by targeted add-on tiers and limited listening hours for casual users. Its recent introduction of Page Match technology, which allows listeners to transition between a physical book or e-book and the corresponding audio track by scanning a page, signals a broader strategy of bridging analog and digital reading rather than replacing it. Coupled with new audiobook charts in key markets, the feature aims to reduce discovery friction and make audiobooks feel native within a broader content routine. Apple Books continues to emphasize cross-device continuity and high-quality narration within its hardware ecosystem, while Google Play Books focuses on accessibility, Android-level integration, and publisher-facing distribution tools. The common thread across these approaches is that technical differentiation is shifting from catalog size alone toward seamlessness, discovery, and cross-format interoperability.
Regulatory and Privacy Dynamics
Regulation is reshaping the operating environment in ways that directly affect platform architecture and expansion economics. Net neutrality challenges and regulatory rollbacks in the United States have introduced uncertainty around traffic prioritization and throttling, which matters for platforms that depend on consistent broadband delivery for uninterrupted playback at scale. More immediately, data sovereignty and localization requirements have expanded in scope and geography. Multiple U.S. states have enacted comprehensive privacy regimes, with new provisions taking effect in 2026 across additional jurisdictions, while EU frameworks continue to require control over where listening and behavioral data is processed. For global platforms, this means that a single data pipeline is no longer sufficient. Compliance now intersects with product design, customer support, recommendation engines, and partnership structures. Companies that design architecture with regional data handling from the outset gain advantages in market entry speed and partnership eligibility, while those that retrofit compliance later face integration costs and reputational exposure.
Consumer Habits and Demand-Side Shifts
Demand is being reinforced by durable changes in listening behavior. In the United States, more than half of adults aged eighteen and older have listened to an audiobook, with a meaningful subset engaging daily and a large majority identifying accessibility as an important factor in their listening choices. In the United Kingdom, weekly audio reach has expanded substantially since 2019, with average weekly listening among users approaching ten hours. These figures indicate that audiobooks are no longer an occasional substitute for reading; they are becoming a routine component of daily commutes, exercise, and work-adjacent consumption. Accessibility is particularly significant because it expands the addressable audience beyond convenience-driven users to include listeners who rely on audio for visual, cognitive, or mobility-related reasons. This broadens the market’s base and reduces sensitivity to price-only competition, provided platforms can demonstrate inclusive design and quality narration.
Supply-Side and Cost Structure Evolution
On the supply side, the publisher-distributor relationship is evolving as production scale and catalog breadth increase. RBmedia’s record results in early 2026, driven by catalog growth, bestseller traction, and award wins across major platforms, illustrate how strong production pipelines continue to feed consumption across multiple endpoints simultaneously. At the same time, the cost of hosting, streaming, and personalizing large catalogs is rising as usage intensifies. The energy footprint associated with data centers supporting digital content delivery is climbing, and the pressure to manage that footprint is becoming part of the cost structure conversation. Platforms that cannot align catalog growth with storage efficiency, streaming optimization, and smarter recommendation logic will find it harder to sustain margin expansion as competition intensifies and subscription pricing comes under scrutiny.
Competitive Landscape and Leading Strategies
The competitive environment is shaped by a mix of platform-led, ecosystem-led, and publisher-led models. Audible remains the dominant global platform, leveraging an extensive catalog and Amazon ecosystem integration to anchor subscription plans, credits, and exclusive originals. Its recent launch of a lower-priced Standard plan in key markets reflects a strategic response to integrated streaming offerings that have blurred the line between dedicated audiobook services and broader entertainment subscriptions. By creating a more accessible entry point, Audible is seeking to defend share without diluting its premium positioning.
Spotify’s approach is distinct because it treats audiobooks as one layer inside a larger listening subscription rather than a standalone product. Its Audiobooks add-on, limited casual listening hours, and original catalog of more than half a million English-language titles are supported by tools like Page Match and integrated charts that aim to strengthen discovery. The partnership with Bookshop.org, enabling physical book purchases directly through the app for U.S. and UK users, indicates a strategy of building a multi-format book journey rather than competing purely on digital playback. This positions Spotify as a habit aggregator, linking music, podcasts, and audiobooks within a single subscription logic.
Apple Books and Google Play Books continue to capitalize on device and ecosystem reach. Apple emphasizes seamless syncing across iOS and macOS, high-quality narration, and broad catalog access optimized for its user base. Google focuses on direct sales, Android integration, and distribution support for publishers, with an emphasis on accessibility and cross-device listening. Both benefit from installed base advantages, though their monetization leans more toward transactional access and ecosystem reinforcement than subscription-exclusive exclusivity.
European and multi-format players bring a different set of strengths. Storytel operates as a subscription-based audiobook and ebook streaming service with strong European presence and expanding English-language reach through acquisitions. Scribd, now operating under the Everand brand, shifted to a credit and unlock model that provides access to a rotating audiobook catalog alongside ebooks and magazines, reflecting a pivot toward controlled access economics rather than unlimited consumption. Rakuten Kobo offers Kobo Plus with dedicated audiobook plans and combined ebook and audiobook access, integrated with e-reader hardware, while Audiobooks.com, now part of Storytel, maintains a credit-based subscription model with family plans and offline listening.
Libro.fm occupies a differentiated niche by supporting independent bookstores through an affiliate model, combining purchases and subscriptions with a social impact proposition. RBmedia sits outside the direct consumer interface but remains strategically important as a major publisher with a vast catalog distributed across Audible, Spotify, Apple, Google Play, and library platforms. Its performance underscores the centrality of production and licensing quality to platform success.
The overall landscape is moving toward selective consolidation and functional differentiation. Integrated mega-platforms are competing on ecosystem bundling and discovery tools, while specialist services are competing on catalog curation, format blending, and partnership models. New entrants face steep challenges in catalog acquisition and user acquisition costs, but there is room for differentiated services that serve specific listener segments, accessibility needs, or regional licensing structures. The likely trajectory is a market with a small number of broad-scale platform leaders, a set of strong regional or format-specialist services, and a publisher layer whose influence depends on the quality and breadth of rights management.
Forecast Outlook: Trends and Commercial Implications
Over the next three to five years, one of the clearest trends will be deeper format convergence. Audiobooks will increasingly be embedded within broader listening and reading journeys, supported by tools that link physical books, e-books, and audio tracks. Platforms that make switching frictionless and provide credible cross-format discovery will capture more habitual usage and reduce churn. The commercial opportunity here is not simply more titles; it is a more integrated recommendation and purchase path that increases lifetime value without requiring exaggerated catalog inflation.
PW Consulting
A second trend is the growing importance of data governance and regional readiness as competitive factors. As privacy and localization rules broaden, platforms that can demonstrate transparent data handling, modular architecture, and compliant cross-border operations will be better positioned for expansion into regulated markets and partnership-dependent channels such as libraries and publisher networks. The opportunity lies in turning compliance maturity into market access speed and trust-based differentiation, particularly for enterprise and institutional buyers who weigh risk exposure alongside content quality.
A third trend is the continued pressure on infrastructure economics. As consumption scales, the cost of delivery, storage, and personalization will require more disciplined engineering and more intelligent catalog management. The commercial implication is that margin leadership will increasingly favor operators who can balance catalog breadth with hosting efficiency, streaming optimization, and selective personalization. Platforms that rely on indiscriminate catalog growth without cost-aware design may find growth harder to convert into profitability.
These trends carry uncertainty. Pricing pressure could intensify if bundled subscriptions continue to blur boundaries between audiobooks and adjacent content. Regulatory shifts could alter traffic delivery assumptions and increase compliance overhead. Accessibility and inclusion expectations will likely rise, which is favorable for audience expansion but may raise production and interface standards. The net result is a market with strong growth potential, but where strategic advantage depends on execution quality as much as market momentum.
Strategic Actions for Decision-Makers
For platform operators and content businesses, the priority is to treat listening experience design as a growth lever rather than a feature layer. Investments in cross-format discovery, seamless switching, and accessibility-minded interfaces are likely to yield more retention and expansion than catalog volume alone. At the same time, infrastructure and data architecture should be revisited with an eye to regional compliance and cost efficiency, because these factors are becoming gating conditions for scale rather than administrative details.
Worldwide Online Books Market
For investors and strategic partners, the relevant question is which business models are most resilient under bundling pressure and which operators have durable advantages in catalog rights, discovery quality, and ecosystem reach. Platforms with strong integration into broader habits, credible accessibility positioning, and disciplined cost structures are better placed to convert growth into sustainable economics. Evaluating exposure to regional privacy and localization requirements should also be part of due diligence, especially where expansion plans depend on multi-market data handling.
For publishers, distributors, and procurement teams, the focus should be on partnership structures that preserve reach while managing cost and compliance risk. Multi-platform distribution remains valuable, but selection should account for audience overlap, device reach, and the platform’s ability to support accessibility and discovery that aligns with target listener behavior. In a market where concentration and regulation are both intensifying, timely and granular intelligence on segment dynamics, platform strategy, and regional requirements is essential for allocating resources and negotiating terms with confidence. More detailed breakdowns of segment dynamics, platform-level positioning, and regional considerations are available in the full PW Consulting study, which provides the depth needed for planning in a market that is moving quickly and becoming more structurally complex.
For detailed analysis of this topic, please visit the official page: Worldwide Online Audiobook Site Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Conductive Acetylene Black Market: Why 11.45% CAGR Alters Li-ion Battery Competition
By pmarketresearch, 2026-09-18
Global Conductive Acetylene Black Market: Strategic Trends and Commercial Opportunities (2025–2032)
Market Landscape and Core Challenges
The global conductive acetylene black market for lithium-ion batteries has entered a period of accelerated expansion, driven by the rapid electrification of transportation and the scaling of stationary energy storage. From 2020 to 2025, the market grew from approximately 251.2 million USD to 428.5 million USD, reflecting a compound annual growth rate of 11.45 percent. Forward projections extend this trajectory through 2032, with revenue expected to surpass 915 million USD by the end of the forecast period. This growth is not merely incremental; it represents a structural shift in how battery manufacturers approach conductivity enhancement, formulation optimization, and long-term supply chain resilience.
At this scale, the market is characterized by moderate concentration. The top three players command roughly 58.4 percent of global revenue, while the top five capture approximately 76.25 percent. This concentration indicates a mature yet still evolving competitive field, where established suppliers hold significant technological and distribution advantages, but where regional expansion, capacity investments, and product differentiation are actively reshaping market shares. The dominance of powder-form products over granular alternatives reflects the industry's continued preference for fine-particle additives that integrate seamlessly into slurry processing and electrode coating workflows.
Despite the robust growth trajectory, several structural challenges are creating inflection points for suppliers, buyers, and investors.
First, raw material sourcing and carbon intensity are becoming critical differentiators. Acetylene black production depends heavily on acetylene gas, which is traditionally derived from calcium carbide or emerging low-carbon plasma processes. The energy intensity and environmental footprint of acetylene generation directly affect both cost structures and regulatory compliance, especially as battery supply chains face increasing scrutiny over lifecycle emissions. Firms that cannot secure reliable, lower-carbon acetylene feedstocks or demonstrate verifiable decarbonization pathways risk marginalization in premium segments and markets with stringent sustainability requirements.
Second, the demand profile is shifting toward larger-format cells and high-energy-density chemistries, which place new performance demands on conductive additives. Electric vehicle batteries are increasingly specifying thicker electrodes, silicon-blended anodes, and high-nickel cathodes. Each of these developments alters the rheological behavior of electrode slurries and the percolation thresholds required for optimal conductivity. Conductive acetylene black suppliers must therefore balance particle morphology, surface area, purity, and electrolyte retention to meet expanding technical specifications without compromising processability or cycle life.
PW Consulting
Third, capacity expansion and geographic realignment are introducing both opportunities and execution risks. As demand scales across Asia Pacific, Europe, and North America, suppliers are investing in new production lines and regional manufacturing footprints. However, large-scale capacity additions require long lead times, substantial capital, and coordinated feedstock agreements. Delays in plant commissioning, feedstock supply disruptions, or misalignment between regional demand growth and localized production can create temporary bottlenecks, price volatility, and qualification bottlenecks in tightly controlled automotive supply chains.
These challenges are not simply headwinds; they are reshaping the strategic priorities of the market. Suppliers that proactively address feedstock sustainability, technical customization, and regional supply security are positioning themselves to capture premium value, while buyers are increasingly factoring carbon intensity, qualification timelines, and supply continuity into procurement decisions.
Key Drivers Shaping the Market
Technology Innovation and Product Performance
The most immediate driver of market growth is the continuous push for higher battery performance, particularly in energy density, power delivery, and cycle stability. Conductive acetylene black serves as a critical enabler in lithium-ion electrode architectures by establishing conductive pathways, improving slurry dispersion, and maintaining contact between active materials and current collectors over repeated cycling. As battery manufacturers pursue higher-voltage cathodes, silicon-containing anodes, and more aggressive fast-charging profiles, the functional requirements for conductive additives become more demanding.
Lithium Ion Battery Market
Ultra-pure acetylene black grades with minimal metallic impurities are gaining importance in these applications. Lower impurity levels reduce side reactions at electrode interfaces, improve electrolyte retention, and support more consistent electrochemical performance. This has encouraged suppliers to advance purification processes, control particle morphology more tightly, and develop grades tailored to specific cell formats and chemistries. The result is a market that is moving away from commoditized carbon additives toward application-specific, performance-differentiated products.
Another technological shift is the growing emphasis on low-carbon production. Several industry initiatives are targeting cleaner acetylene generation pathways, including plasma-based processes that can reduce reliance on traditional carbide routes. When paired with efficiency improvements in reactor design and downstream processing, these approaches can lower both operating costs and emissions intensity. For battery makers under increasing pressure to demonstrate supply chain decarbonization, low-carbon acetylene black can become a differentiating input, particularly for premium electric vehicle and energy storage programs.
Policy and Regulatory Environment
Policy frameworks are accelerating demand while simultaneously shaping supply-side behavior. Broader electrification targets, vehicle emission standards, and energy storage deployment incentives continue to expand the addressable market for lithium-ion batteries. At the same time, governments and development agencies are increasingly supporting industrial projects that reduce carbon exposure in critical material supply chains.
Public support for low-carbon acetylene technologies illustrates this dynamic. Subsidies and cooperative financing have been directed toward initiatives that accelerate mass-production technology for lower-carbon acetylene used in conductive carbon black. Such interventions matter because they reduce the commercial risk associated with scaling new feedstock routes and can shorten the timeline between process development and commercial availability. For established suppliers, these programs can provide additional leverage to invest in capacity and process upgrades. For newcomers, they can help bridge the gap between pilot-scale validation and meaningful market entry.
Regulatory attention is also influencing qualification and procurement practices. Automotive and energy storage customers are extending their supplier assessment criteria beyond cost and performance to include traceability, environmental impact, and supply continuity. In this environment, suppliers that can document consistent quality, transparent sourcing, and credible decarbonization actions are better positioned to secure long-term contracts and participate in multi-year platform programs.
Demand-Side Changes in Consumer and Enterprise Behavior
Demand for conductive acetylene black is being pulled upward by two distinct but converging channels. In the mobility sector, electric vehicle production continues to scale across passenger cars, commercial fleets, and two-wheelers, with battery packs growing in both absolute volume and cell count. Manufacturers are increasingly designing platforms that require consistent, high-quality conductive additives across large production runs, reinforcing the need for reliable supply and repeatable material performance.
In the stationary storage segment, growth is being driven by grid integration, renewable firming, and commercial and industrial energy management. While energy storage systems currently represent a smaller share of acetylene black consumption than electric vehicle batteries, the segment is expanding as project developers seek batteries with longer service life and more stable performance over frequent charge-discharge cycles. This introduces a different set of priorities: durability, consistency, and cost efficiency over extended operational horizons. Suppliers that can demonstrate value across both high-energy mobility applications and long-duration storage applications are expanding their addressable market beyond a single end-use vertical.
Supply Chain Reconfiguration and Cost Structure Dynamics
The supply chain for conductive acetylene black is undergoing geographic and structural change. Traditional supply hubs remain important, but new production capacity is being added in regions selected for feedstock proximity, customer access, and logistics efficiency. This is particularly visible in the establishment of dedicated acetylene black facilities that are designed to serve regional battery manufacturing ecosystems.
A notable example is the construction of a new acetylene black production facility in Texas, intended for battery-grade conductive additives. Once operational, the plant is expected to combine with existing European capacity to substantially increase total manufacturing output and improve service levels for North American and global customers. Its development is supported by long-term acetylene supply arrangements with a neighboring industrial site, highlighting how feedstock integration can reduce cost volatility and improve supply reliability. Projects of this type signal a broader trend: capacity expansion is increasingly tied to feedstock security, regional customer proximity, and the ability to qualify materials within demanding automotive supply chains.
At the same time, financing and partnership structures are evolving to support growth. In one recent case, a major public lender provided financing to support a joint venture focused on acetylene black manufacturing and sales for lithium-ion and next-generation batteries. Such arrangements reflect the capital intensity of scaling capacity and the importance of aligning funding with regional demand strategies. They also demonstrate how established players are using partnerships and joint ventures to extend geographic reach while maintaining technical control over product quality.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a small group of well-established producers and a set of strategic moves designed to protect differentiation while expanding reach. Leading companies are not simply competing on volume; they are building position around purity, application engineering, regional supply, and feedstock-backed capacity.
Denka Company Limited stands out for its focus on ultra-pure acetylene black designed specifically for lithium-ion and next-generation batteries. Its product strategy emphasizes minimal metallic impurities, high electrical conductivity, and strong electrolyte retention, all of which are directly relevant to performance-sensitive cell programs. Denka has also been extending its manufacturing footprint through a joint venture in Thailand, creating an additional production base to support stable supply amid rising global demand. Complementing this geographic expansion, the company has pursued support for lower-carbon acetylene mass-production technology, aligning product quality with evolving sustainability expectations.
Orion Engineered Carbons is pursuing a different but complementary strategy centered on regional capacity expansion and integrated feedstock access. Its battery-grade acetylene-based conductive carbon black is positioned for lithium-ion applications, with production operations in France and a major new facility under construction in Texas. The Texas project is intended to meaningfully increase effective manufacturing capacity for acetylene-based additives, supported by a long-term acetylene supply relationship with a neighboring chemical site. This approach illustrates how established carbon black producers can leverage site integration, regional customer proximity, and process scale to strengthen their position in the battery materials segment.
IRPC Public Company Limited has focused on premium-grade acetylene black for use as conductive carbon in battery manufacturing, emphasizing product quality and reliability within its regional operating context. Soltex Inc. serves the market by supplying acetylene black raw materials for lithium-ion and other battery applications, with a product range that supports multiple grades and use cases. These suppliers demonstrate that the market is not limited to a single business model; there is room for producers with different scale positions, regional advantages, and level of vertical integration, provided they can meet specification requirements and qualification standards.
Binders for Lithium Ion Batteries Market
Several developments in recent years highlight how these strategies are playing out in practice. Orion has showcased its new Texas facility as a key step in expanding battery-grade acetylene black capacity, with production expected to begin in the second quarter of 2026. Denka has meanwhile advanced its Thai joint venture with financing support, reinforcing its intent to scale manufacturing and sales capabilities for battery-grade acetylene black and next-generation applications. Together, these moves indicate a market where capacity expansion is accelerating, but where expansion is also increasingly tied to feedstock security, regional service, and sustainability positioning.
Looking at broader structural trends, the competitive landscape appears likely to evolve along three directions. First, integration and scale will continue to matter, particularly for suppliers that can ensure feedstock continuity and manage the capital demands of new capacity. Second, differentiation will increasingly depend on technical service, purity control, and the ability to support customer qualification across diverse cell designs. Third, the market may see selective new entry or capacity-led pressure in specific regions, especially where local demand growth and feedstock availability create favorable conditions. However, full commoditization is unlikely in the near term because battery manufacturers continue to reward suppliers that can deliver consistent performance, low impurities, and credible sustainability credentials.
Future Trends and Commercial Implications
Over the next three to five years, the conductive acetylene black market is likely to be shaped by the intersection of performance requirements, decarbonization pressure, and regional supply chain build-out. Three trends stand out.
The first trend is the widening gap between standard and premium conductive additives. As cell designs become more advanced and qualification standards tighten, battery manufacturers will increasingly distinguish between general-purpose carbon black and tailored grades that offer higher purity, better electrolyte retention, and more controlled morphology. This will reward suppliers that invest in application engineering and consistent manufacturing quality, while pressuring those that remain competing primarily on price in undifferentiated segments.
The second trend is the growing commercial relevance of lower-carbon production pathways. Even where regulatory mandates are not yet explicit, procurement teams are beginning to consider carbon intensity as part of multi-criteria supplier evaluation. Suppliers that can verify lower-emission acetylene routes, efficient processing, and transparent lifecycle data will be better positioned to participate in premium programs and long-term partnerships. The practical opportunity here is not just environmental; it is commercial differentiation in a market where sustainability claims must be substantiated by process and sourcing choices.
The third trend is a more regionally balanced supply footprint. Demand growth is not uniform across geographies, and battery manufacturers increasingly prefer suppliers that can deliver consistent volumes with shorter logistics loops and stronger local technical support. As new capacity comes online and joint ventures expand, the market may become less dependent on a narrow set of supply origins. This could improve supply resilience for buyers while also raising the bar for competitors that cannot match regional responsiveness or feedstock security.
These trends create commercial opportunities for suppliers that can combine product performance with supply reliability and credible sustainability attributes. For buyers, the opportunity lies in securing qualified materials early, aligning formulation strategies with evolving cell designs, and reducing exposure to single-source risk. The main uncertainties include the pace of new capacity commissioning, potential volatility in feedstock availability and cost, and the possibility that demand growth diverges from current expectations if vehicle adoption patterns or energy storage deployment shift. Any of these factors could alter pricing dynamics and the relative attractiveness of different capacity investments.
Strategic Actions for Decision-Makers
For battery material manufacturers and additive suppliers, the priority is to align product development with the performance and sustainability expectations of next-generation cells. This means investing in ultra-pure grades, improving process consistency, and building the technical service capabilities needed to support qualification across multiple customer platforms. Suppliers should also evaluate feedstock strategies carefully, since long-term access to reliable acetylene sources and lower-carbon production options can become a durable competitive advantage rather than a peripheral consideration.
For investors, the market offers exposure to a structurally growing segment, but returns will depend on choosing the right entry points and business models. Capacity expansion alone is not a guaranteed path to value creation if it is not supported by feedstock integration, regional demand alignment, and differentiated product positioning. Due diligence should focus on qualification status, customer concentration, sustainability credentials, and the credibility of expansion timelines. Projects that combine technical differentiation with defensible supply chains are more likely to translate market growth into durable margin potential.
For procurement and supply chain leaders, the strategic imperative is to move beyond short-term price optimization and build resilience into conductive additive sourcing. Multisourcing strategies, early qualification of alternative grades, and close collaboration with suppliers on formulation and performance requirements can reduce risk in high-volume programs. Procurement teams should also consider how carbon intensity and supply continuity may affect future sourcing criteria, particularly in markets where battery customers are extending sustainability expectations through the value chain.
Given the speed at which capacity plans, qualification pipelines, and sustainability expectations are evolving, decision-makers benefit from detailed, segmented data on demand by region and application, product form dynamics, and supplier-level capacity and strategy. A comprehensive market study can help translate these trends into more precise sourcing plans, investment theses, and product roadmaps. For those evaluating next steps, accessing the full report provides a deeper view of segmentation, competitive positioning, and the operational and commercial variables that will shape the market through the end of the decade.
For detailed analysis of this topic, please visit the official page: Worldwide Conductive Acetylene Black for Li-ion Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Magic Carpet Ski Lifts Market: How the 5.85% CAGR Trajectory Reshapes Strategy
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Magic Carpet Ski Lifts Market
Market Landscape and Core Challenges
The global market for magic carpet ski lifts has established itself as a critical enabler of accessible snow sports, demonstrating consistent growth over the past half-decade. Valued at approximately $168.45 million in 2020, the sector has expanded to reach an estimated $228.4 million by 2025. Projections indicate a steady compound annual growth rate of 5.85 percent through the forecast period extending to 2032, with anticipated revenues approaching $342.45 million by the end of that horizon. This trajectory reflects a maturation phase where surface conveyor technology has transitioned from a niche accessory to a standard infrastructure component in modern snow sports venues. The steady upward curve underscores the increasing reliance on mechanical assistance to facilitate beginner learning curves and operational efficiency across diverse resort environments.
Despite this positive momentum, the industry faces several structural hurdles that define the current investment and operational landscape. One primary challenge is the regulatory tightening surrounding surface lifts and conveyor systems. Standards such as ANSI B77.1-2022 now impose rigorous design, construction, operation, and maintenance safety requirements specifically for surface lifts, tows, and conveyors. Compliance demands not only capital expenditure but also ongoing operational vigilance, which can strain smaller operators and manufacturers lacking dedicated safety engineering teams. The complexity of meeting these evolving standards creates a barrier to entry while simultaneously rewarding established players who can navigate certification processes efficiently.
A second significant friction point involves the balance between cost efficiency and performance expectations. While polymer synthetic belts dominate volume due to their durability and lower maintenance profiles compared to rubber alternatives, the initial capital outlay for enclosed, heated, or enclosed-gallery systems remains substantial. Operators in emerging markets or smaller regional resorts often struggle to justify the ROI against rapid technological obsolescence. The pressure to upgrade existing infrastructure to match tourist expectations for comfort and speed creates a dichotomy where investment is necessary but financially burdensome for cash-flow-sensitive businesses.
Finally, the market grapples with the geographic concentration of demand and supply. The revenue distribution shows a heavy weighting toward developed regions with established ski cultures, creating vulnerabilities tied to climate variability and seasonal dependency. Manufacturers must decide whether to deepen penetration in saturated markets or pursue expansion into regions where snow sports infrastructure is still developing. This geographic nuance complicates strategic planning, as a one-size-fits-all approach rarely optimizes risk-adjusted returns across the global footprint. The interplay between regulatory compliance, cost structures, and regional demand variance defines the current competitive equilibrium.
Key Drivers of Market Change
Several interconnected forces are accelerating the evolution of the magic carpet ski lifts market, reshaping value chains and redefining operational benchmarks. Understanding these drivers is essential for stakeholders aiming to align their strategies with the direction of industry momentum.
Technological Innovation and Design Enhancements
Engineering advancements continue to drive differentiation in the surface lift sector. The shift from basic open-belt systems to modular, enclosed, and variable-speed designs represents a fundamental change in how operators approach guest experience and safety. Modern installations increasingly feature galvanized steel construction and customizable belt widths that accommodate varying throughput requirements. The ability to transport components globally and assemble them locally, as seen in recent cross-border projects, highlights the globalization of manufacturing capabilities. This modularity reduces on-site construction time and allows for easier maintenance or replacement of worn sections, directly addressing the operational cost concerns that plague resort managers. Furthermore, innovations in speed settings up to 1.2 meters per second and lengths exceeding 400 meters enable higher capacity throughput, making these systems viable replacements for traditional tow lifts in busy learning zones.
Regulatory and Safety Standards Evolution
The regulatory environment acts as both a constraint and a catalyst for market development. Updated safety frameworks, such as the ANSI B77.1-2022 standard, establish comprehensive requirements for passenger ropeways including specific sections for surface lifts and conveyors. These regulations mandate rigorous attention to design integrity, construction quality, operational protocols, and maintenance schedules. While compliance adds complexity, it also elevates the baseline for quality and reliability across the industry. Manufacturers who proactively integrate these standards into their R&D and production processes gain a competitive edge, as resort operators increasingly prioritize vendors who can assure regulatory adherence and minimize liability risks. The formalization of safety expectations effectively filters out lower-quality entrants and consolidates demand around established, compliant suppliers.
Demand-Side Transformation in Snow Sports
Consumer behavior and resort business models are shifting in ways that favor automated, accessible lift solutions. There is a growing emphasis on reducing the learning curve for beginners and families, which drives demand for magic carpets in ski school areas and beginner zones. Resorts are increasingly viewing these systems not just as conveyor belts but as experiential assets that can improve throughput, reduce wait times, and enhance the overall visitor experience. The trend toward enclosed designs protects users from weather elements, extending the usable season and improving comfort, which aligns with the broader push toward year-round or extended-season business models in mountain tourism. Additionally, the rise of indoor ski facilities in regions without natural snowfall creates a distinct demand channel for durable, climate-controlled conveyor systems that can operate reliably in controlled environments. This diversification of application venues broadens the addressable market beyond traditional outdoor resorts.
Supply Chain and Cost Structure Shifts
Cost dynamics are being reshaped by material choices and global logistics capabilities. The prevalence of polymer synthetic belts in the market reflects a broader industry preference for materials that offer longevity and reduced maintenance compared to traditional rubber belts. However, supply chain resilience has become a key consideration, especially as manufacturers source components across borders and manage assembly schedules across different hemispheres. The ability to efficiently transport and install systems, such as units fabricated in Europe and deployed in North America, demonstrates a mature logistics network that supports rapid deployment. Yet, fluctuating raw material costs and transportation expenses can introduce volatility into pricing strategies. Operators and manufacturers alike are increasingly looking toward localized support networks and modular designs that allow for easier replacement parts sourcing, mitigating the risks associated with long-distance supply disruptions.
PW Consulting Automotive & Machinery Research Center
Competitive Landscape and Leading Strategies
The market structure reveals a landscape characterized by a mix of specialized innovators and globally scaled operators, with concentration levels indicating a degree of consolidation among top players. The top three companies account for approximately 52.3 percent of market revenue, while the top five hold around 68.7 percent. This concentration suggests that while the market is not a pure monopoly, scale and brand recognition provide significant advantages in securing large contracts and managing supply chain complexities.
Magic Carpet Lifts / RMCE, Inc. represents a legacy player with deep roots in the sector. Founded as the original inventor of the Magic Carpet Boardwalk conveyor ski lift, the company has built a reputation around custom heavy-duty modular surface conveyor systems. Their focus on galvanized steel construction and global component support positions them as a provider of robust, long-life infrastructure solutions. By catering to ski resorts, water parks, and theme parks, they have diversified their application base beyond snow sports, mitigating seasonality risks. Their strategic positioning hinges on customization and durability, appealing to operators who prioritize system longevity and specific site requirements over off-the-shelf solutions. The ability to offer global component support further strengthens their value proposition for international clients seeking reliable maintenance and parts availability.
Sunkid stands as a global market leader with a vastly extensive installation footprint, boasting over 4200 installations across more than 80 countries. Their dominance is built on a comprehensive product portfolio that includes modular designs extending beyond 400 meters, variable speed controls, multiple belt widths, and enclosed gallery options. Sunkid's strategy emphasizes scalability and versatility, targeting ski schools, beginners, and replacement projects for traditional lifts. Their recent activity underscores this focus; for instance, a 60-meter magic carpet installation at Rotarun Ski Area involved transportation from Austria and local assembly for the winter season, highlighting their ability to execute complex international deployments. Additionally, Angel Fire Resort's installation of a new longer, faster, enclosed magic carpet for ski school use illustrates the type of high-spec projects that drive the demand for advanced surface lift technology. Sunkid's scale allows them to absorb production volumes and leverage procurement efficiencies that smaller competitors may struggle to match.
The competitive dynamics are evolving toward a blend of consolidation and specialized differentiation. While leading players capture the bulk of revenue, there remains room for niche players who can offer rapid deployment, cost-effective modular solutions, or specialized technical support in underserved regions. The trend toward enclosed, faster, and longer systems indicates that competition is increasingly shifting from basic functionality to performance metrics, user experience, and total cost of ownership. New entrants face the challenge of meeting stringent safety standards and building trust with resort operators who are risk-averse regarding critical infrastructure. However, opportunities exist in regions where infrastructure is growing rapidly, or in applications where indoor facilities require specialized conveyor systems that differ from outdoor requirements. The market is likely to see continued pressure on pricing for standard configurations while premium, customized, or high-performance systems command higher margins. Strategic partnerships between manufacturers and resort developers, as well as focus on aftermarket service and support, are becoming key differentiators in securing long-term customer relationships.
Future Trends and Outlook
Looking ahead to the next three to five years, several trends are poised to shape the trajectory of the magic carpet ski lifts market. These trends are not merely incremental improvements but represent shifts in how value is created and captured within the sector.
Stairlift Market
Expansion of Enclosed and Climate-Adaptive Systems
The demand for enclosed, heated, and weather-protected conveyor systems is expected to accelerate. As resorts seek to maximize season length and improve guest comfort, particularly for learning areas where user retention is critical, enclosed designs offer a tangible competitive advantage. This trend connects directly to commercial opportunities in retrofitting existing open systems with gallery enclosures or prioritizing enclosed configurations in new builds. Manufacturers that can offer cost-effective enclosure solutions with integrated safety and weatherproofing features will likely capture a growing share of upgrade projects. The data supporting this shift is visible in recent installations focusing on faster, enclosed setups for ski school usage, signaling a move toward higher-specification infrastructure.
Geographic Diversification and Emerging Market Penetration
While established regions continue to dominate revenue, the next phase of growth will increasingly come from geographic diversification. Regions with developing snow sports infrastructure and growing tourism investment present opportunities for market penetration. The modular and transportable nature of modern magic carpet systems facilitates entry into markets where local manufacturing capacity may be limited but demand is rising. Companies that can navigate local regulatory environments, establish assembly or support partnerships, and offer financing or turnkey solutions will be well-positioned to capitalize on this expansion. However, this trend carries the risk of over-extension if demand projections in emerging markets do not materialize as expected, requiring careful validation of local resort development pipelines.
Integration of Smart Monitoring and Operational Efficiency
The future of surface lifts will likely involve greater integration of monitoring technologies, predictive maintenance capabilities, and data-driven operational adjustments. As resorts digitize their operations, the ability to track throughput, detect wear patterns, and optimize speed settings based on real-time guest flow becomes a valuable asset. This trend opens opportunities for manufacturers and service providers to offer value-added software and telemetry services alongside hardware. It also raises the bar for competitors who rely on analog, manually managed systems. The risk here lies in the complexity of integration and the need for interoperability with existing resort management systems, which could slow adoption if not addressed through open standards or user-friendly interfaces.
Worldwide Capsule Elevator Market
Actionable Insights for Decision Makers
For manufacturers, the priority should be doubling down on modular design capabilities and regulatory compliance as core competencies. Investing in product lines that allow for rapid assembly, easy expansion, and adherence to international safety standards will differentiate offerings in a market where operators value reliability and ease of maintenance. Developing partnerships for localized support and after-sales service can also mitigate the risks associated with global deployments and enhance customer retention.
Investors evaluating opportunities in this sector should focus on companies that demonstrate a balance of scale, technological differentiation, and geographic agility. The concentration of revenue among top players indicates that market share is valuable, but the growth trajectory suggests that innovation and service capabilities will determine long-term winners. Assessing a company's pipeline of enclosed and high-performance systems, as well as their exposure to emerging markets and indoor facilities, can provide a clearer picture of future growth potential. Additionally, evaluating supply chain resilience and material cost management strategies is crucial given the volatility inherent in global manufacturing.
For procurement teams and resort operators, the focus must shift toward total cost of ownership and lifecycle performance rather than upfront price alone. Selecting suppliers with proven track records in safety compliance and robust component support reduces operational risk and downtime. Considering the strategic fit of enclosed versus open configurations based on specific site conditions and guest demographics can optimize ROI. Engaging with manufacturers early in the planning phase to explore modular scalability and future-proofing options ensures that infrastructure investments remain relevant as demand patterns evolve.
Navigating this dynamic landscape requires access to granular data and nuanced strategic guidance. Stakeholders seeking detailed segmentation analysis, competitive benchmarking, and customized scenario planning will benefit from comprehensive research resources that provide deeper visibility into market mechanics and forward-looking indicators.
For detailed analysis of this topic, please visit the official page: Magic Carpet Ski Lifts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Doxylamine Market Analysis 2026: Decoding 3.96% CAGR and $625M Growth
By pmarketresearch, 2026-09-18
Doxylamine Market Outlook: Navigating Growth Trajectories and Strategic Opportunities Through 2032
Market Overview and Core Challenges
The global doxylamine market has demonstrated resilience and steady expansion over the past half-decade, evolving from a mature antihistamine foundation into a strategically positioned segment within both over-the-counter sleep aids and prescription antiemetic therapies. Valuation trends from 2020 through 2025 reflect a compound annual growth rate of approximately 3.96 percent, with the market reaching a baseline valuation in the mid-470 million dollar range by 2025. Forward projections extend through 2032, indicating a phase of moderate but sustained expansion that will be shaped by formulation diversification, regulatory clarity, and shifting therapeutic demand patterns.
Despite this constructive trajectory, several structural and operational challenges demand careful navigation. Supply chain volatility remains a persistent concern, particularly around the procurement of high-purity active pharmaceutical ingredients and the management of inventory cycles. Seasonal and cyclical demand fluctuations, especially in regions where doxylamine is heavily utilized for cold and allergy relief, can pressure manufacturing planning and create uneven revenue streams. Additionally, regulatory divergence across jurisdictions continues to complicate product positioning. While certain formulations enjoy straightforward OTC classification, others face tighter labeling requirements, evolving safety communications, or payer-specific access protocols that influence downstream adoption and commercial execution.
Product positioning and brand equity present another layer of complexity. The market contains well-established legacy sleep-aid brands alongside newer combination therapies targeting pregnancy-related nausea. This duality creates a bifurcated competitive environment where generic and branded strategies must coexist, and where consumer trust, clinical perception, and reimbursement pathways intersect in ways that can accelerate or constrain growth. Companies that rely solely on volume expansion without differentiated value propositions often face margin compression, especially when raw material cost cycles intersect with pricing competition.
For executives and investors, the central challenge is not whether the doxylamine market will continue to grow, but how efficiently organizations can capture value amid shifting cost structures, regulatory nuance, and patient-consumer behavior changes. Strategic positioning will increasingly depend on supply reliability, formulation agility, and the ability to align commercial models with the specific regulatory and reimbursement realities of each therapeutic application.
Key Growth Drivers Shaping the Market
Technology Innovation and Formulation Advancement
Formulation innovation continues to be a meaningful driver in how doxylamine is positioned and consumed. Oral tablet formats remain the dominant delivery mechanism, reflecting established consumer familiarity and manufacturing efficiency. However, the market is gradually accommodating liquid and syrup formats as well as capsule variations, which expand accessibility for patients with swallowing difficulties or specific dosing preferences. These formulation shifts are not merely cosmetic; they support broader patient adherence, enable more flexible titration, and create opportunities for differentiation in crowded OTC categories. In parallel, process improvements in API synthesis and purification are enhancing batch consistency and reducing variability, which matters particularly in regulated combinations where quality uniformity is tightly scrutinized.
PW Consulting
Regulatory Environment and Approval Pathways
Regulatory clarity has become an increasingly important enabler of market expansion. Doxylamine succinate is widely recognized in OTC nighttime sleep-aid classifications, while combination products with pyridoxine have secured specific pathways for managing nausea and vomiting of pregnancy under appropriate oversight. This dual regulatory identity gives the molecule a broader commercial footprint than many single-indication antipathics. Yet regulatory nuance also creates strategic opportunities for companies that invest in compliance readiness, labeling precision, and documentation discipline. Jurisdictions differ in how they treat doxylamine-containing combinations, and manufacturers that anticipate labeling changes, safety communications, and pharmacovigilance expectations are better positioned to maintain uninterrupted market access. The historical context of earlier product withdrawals in related therapeutic categories also reminds industry participants that reputation, safety communication, and transparent clinical positioning remain critical to long-term brand viability.
Demand-Side Behavior and Therapeutic Adoption
Consumer and clinical demand patterns are evolving in ways that reinforce doxylamine relevance across multiple applications. Sleep disturbances, seasonal allergy burdens, and pregnancy-related nausea continue to drive utilization, but the manner in which these needs are addressed is changing. Patients and clinicians increasingly favor products that balance efficacy with tolerability, predictable onset, and clear usage instructions. In the sleep-aid category, consumers seek accessible nighttime solutions with manageable side-effect profiles, while in the pregnancy nausea segment, the availability of well-characterized combination products helps clinicians and patients navigate symptom management with greater confidence. Reimbursement dynamics add another dimension to demand behavior. Certain payer policies require documented trial and failure of separate OTC components before branded combination therapies are authorized, which influences prescribing behavior, patient access, and the commercial calculus for manufacturers developing dual-channel strategies.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by raw material pricing behavior and manufacturing scale decisions. Producer prices for doxylamine succinate experienced a year-over-year decline in late 2025, partly reflecting inventory accumulation during the third quarter and the broader rhythm of demand planning. While such cost movements can temporarily improve margin flexibility, they also highlight the importance of disciplined procurement strategies and inventory management. Manufacturers with diversified sourcing, strong supplier relationships, and the ability to align production schedules with demand forecasts are better equipped to stabilize costs through cyclical fluctuations. At the same time, the presence of multiple international suppliers across North America, Europe, and Asia creates a competitive cost environment that rewards operational efficiency without sacrificing GMP compliance or regulatory documentation quality.
Scopolamine Market
Competitive Landscape and Leading Strategies
The doxylamine market is moderately concentrated, with a significant share held by a group of established players spanning API suppliers, branded combination product developers, and OTC marketers. This concentration reflects a market where scale, regulatory readiness, and distribution relationships matter, but it also leaves room for specialized manufacturers and regional entrants that can serve distinct therapeutic needs or geographic demand pockets. The competitive environment is best understood as a layered ecosystem rather than a single battleground, with different participant groups competing on different axes.
API-focused suppliers form the foundational layer of the market. Companies with GMP compliance, USDMF and EDMF filings, and broad export capabilities provide essential building blocks for both generic manufacturers and branded developers. Their strategic advantage lies in regulatory documentation, batch reliability, and the ability to serve multiple downstream customers across regions. In this segment, differentiation often comes from certification breadth, quality systems, and the capacity to maintain steady supply through demand cycles. These suppliers compete less on consumer-facing brand recognition and more on cost predictability, compliance consistency, and responsiveness to customer formulation requirements.
Branded and combination product developers occupy a more clinically differentiated position. In the pregnancy nausea segment, for example, companies marketing doxylamine succinate plus pyridoxine combinations have built product identities around specific therapeutic use, targeted messaging, and payer navigation. Their advantage comes from clinical branding, patient support ecosystems, and the ability to manage prior authorization and reimbursement requirements in key markets. This group faces a more complex commercial path than pure OTC marketers because access depends not only on consumer demand but also on clinician adoption and payer policies.
OTC sleep-aid marketers represent another major competitive tier, leveraging established brand recognition, retail channel relationships, and accessible package formats. Their strategic positioning centers on consumer trust, shelf visibility, and pricing dynamics within mass-market channels. In a category where many products rely on similar active ingredients, differentiation can be achieved through branding, formulation presentation, dosing convenience, and channel strategy. The presence of strong legacy brand recognition and retail momentum gives incumbents a durable advantage, but it also raises the bar for new entrants who must compete on trust and distribution as much as product performance.
Recent activity illustrates how these competitive layers interact. Licensing and market-access agreements are expanding regional availability of combination therapies, while localized launches are bringing doxylamine-pyridoxine options to new geographies. At the same time, pricing behavior in raw material markets and the management of inventory cycles are shaping short-term margin narratives for manufacturers across the value chain. The broader trend is one of selective integration and targeted expansion rather than uniform consolidation. Some participants are strengthening their position by combining API capability with downstream product strength, while others are focusing on regional niches or specific therapeutic applications where they can build defensible share.
For decision-makers, the key insight is that success in this market rarely comes from a single lever. Competitive advantage is typically constructed through a combination of supply reliability, regulatory compliance, product positioning, channel access, and reimbursement strategy. Companies that align these elements to a clear therapeutic and geographic focus are better positioned to protect margins and expand relevance as the market matures.
Future Trends and Commercial Opportunities
Looking ahead to the next three to five years, several trends are likely to shape how value is created in the doxylamine market. First, formulation and delivery diversification will remain an important growth lever. While oral tablets will continue to anchor the market, expanded use of liquids, syrups, and capsule variants can open access to patient segments that prefer or require alternative formats. Manufacturers that invest in flexible formulation capabilities and clearly communicate usage benefits may capture incremental share, particularly in categories where adherence and ease of administration influence repeat purchase behavior.
Second, regional access expansion for combination therapies is likely to continue. The normalization of licensing agreements and localized product introductions suggests that doxylamine-pyridoxine combinations will keep extending into new markets where pregnancy-related nausea management can benefit from established, well-characterized options. This trend creates opportunities for partners who can navigate local regulatory requirements, distribution networks, and reimbursement expectations. At the same time, it introduces execution risk, since market entry success depends heavily on regulatory alignment, payer dynamics, and clinician acceptance in each jurisdiction.
Third, cost discipline and supply chain resilience will become increasingly decisive competitive factors. Raw material pricing cycles, inventory timing, and manufacturing efficiency will continue to influence margin outcomes. Organizations that build robust procurement planning, maintain compliance-ready production capacity, and anticipate demand variability will be better positioned to protect profitability when input costs fluctuate. This is especially relevant in a market where concentration is meaningful but not absolute, and where multiple international suppliers create both pricing pressure and sourcing optionality.
Paracetamol Market
These trends point to a set of commercial opportunities for organizations willing to act with precision. There is room to strengthen value in the sleep-aid segment through brand trust, channel execution, and patient-friendly formulation choices. There is also opportunity in the pregnancy nausea segment for companies that can combine clinical credibility, payer navigation, and reliable supply. More broadly, the market favors participants who can integrate upstream API reliability with downstream product strategy, rather than those who compete in only one layer of the value chain. Risks remain, particularly around regulatory communication, reimbursement policy changes, and cost cycles that can compress margins if not managed proactively.
Actionable Guidance for Decision-Makers
For manufacturers and suppliers, the priority is to reinforce supply reliability and regulatory readiness while preserving flexibility in formulation and sourcing. Building stronger quality documentation, maintaining certification breadth, and aligning production planning with demand cycles can reduce exposure to cost volatility and improve customer confidence. Companies should also evaluate where formulation diversification or targeted geographic expansion can add meaningful value without stretching operational focus too broadly.
For investors, the market rewards disciplined exposure to companies with clear therapeutic positioning, credible compliance infrastructure, and realistic reimbursement strategies. It is worth distinguishing between businesses that rely mainly on volume and cost competition and those that combine product differentiation with access management in regulated or payer-sensitive segments. Monitoring raw material pricing trends, licensing activity, and regional launch patterns can provide early signals about where competitive advantage is being built or eroded.
For procurement and purchasing leaders, the emphasis should be on supplier resilience, quality consistency, and predictable pricing rather than short-term cost minimization alone. Diversifying sourcing options, validating documentation readiness, and tracking inventory and pricing signals can help mitigate disruption risk. Procurement strategies that incorporate regulatory and supply continuity considerations are better suited to a market where formulation reliability and compliance readiness directly affect downstream product performance.
As the doxylamine market moves through its next phase of moderate growth and structural refinement, the organizations that succeed will be those that pair market awareness with execution discipline. More granular segmentation data, region-specific dynamics, and customized strategic scenarios can help decision-makers translate these high-level trends into concrete plans. A full market research report offers deeper breakdowns across formulation, application, regional demand patterns, competitive positioning, and pricing context, along with tailored recommendations designed to support practical strategy development.
For detailed analysis of this topic, please visit the official page: Worldwide Doxylamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com